
When was the last time you stood in a queue to move your money? A long time ago, probably. These days it takes a tap on a screen.
Want to be part of that story? Then start by finding the right tech partner among the top 20 fintech app development companies in UK.
The UK fintech market is estimated at USD 21.44 billion in 2026 and is projected to reach USD 43.92 billion by 2031, growing at 15.42% a year. Consumer adoption has never been higher.
But building a fintech app is not like building any other app. It means passing FCA scrutiny, handling real-time payments, encrypting sensitive financial data, and making all of it feel effortless to the user.
Most companies can build something that looks like a fintech app. Far fewer can build one that works like one.
This guide helps you find exactly those companies.
- UK fintech is a USD 21.44 billion market in 2026, growing at a 15.42% CAGR to 2031.
- Regulatory fluency is what separates a fintech app development company from a general app developer.
- UK GDPR, PCI DSS, FCA rules, Open Banking standards and AML/KYC compliance are non-negotiable for UK fintech apps.
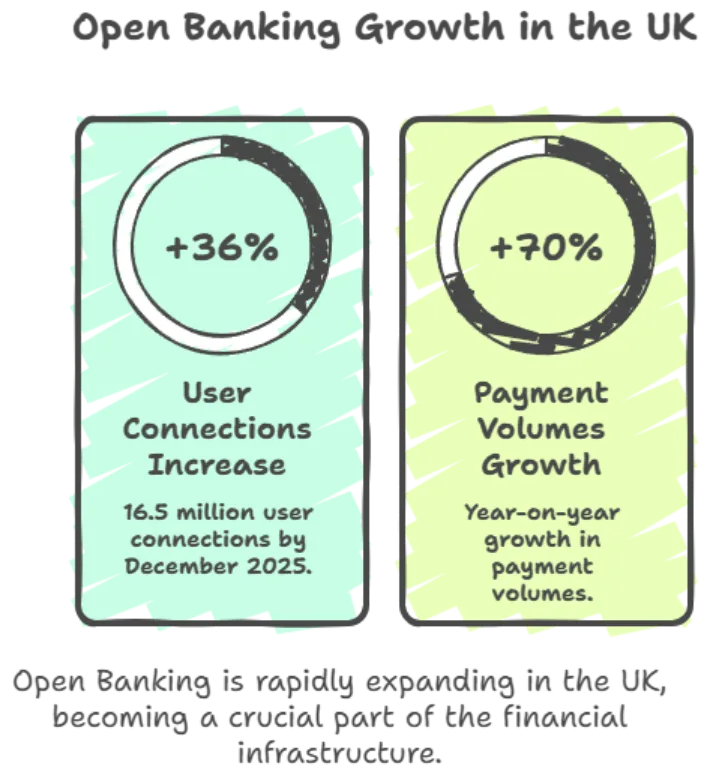
- Open Banking reached 16.5 million user connections in December 2025, up 36% in a year.
- Fintech app development typically starts around £25,000 for an MVP and runs past £400,000 for enterprise platforms.
- The most underestimated fintech costs are compliance, security audits and post-launch maintenance.
- AI and machine learning are now baseline expectations in UK fintech, not differentiators.
- Structured SLAs matter as much as the build, because post-launch support is where fintech apps succeed or fail.
Editorial Disclosure
Brain Station 23This is a well-researched listicle by the Brain Station 23 team. And yes, we included ourselves on this list, so please keep that in mind as you read.
Also note that nobody paid for a spot or a rank, and no company saw the draft before we published it.
If another firm on this list is a better fit for your build, hire them. Just choose wisely. A bad development partner can cost you time, money, and even your project.
List of Top 20 Fintech App Development Companies in UK: 2026 Ranking
| Rank | Company | Core Strength | Founded | Company Size | Best For | Fintech Verticals | Clutch Rating |
|---|---|---|---|---|---|---|---|
| 1 | Brain Station 23 | Cross-border remittance, digital wallets & AI-powered banking | 2006 | 900+ | Startups, SMEs & Enterprises | Payments, Remittance, Digital Banking, FinTech SaaS | 4.9 (21 reviews) |
| 2 | Appinventiv | Enterprise fintech delivery with compliance built in | 2014 | 1,600+ | SMEs & Enterprises | Payments, WealthTech, InsurTech, LendTech | 4.7 |
| 3 | DataArt | Core banking modernisation & capital markets engineering | 1997 | 5,000+ | Enterprises | Capital Markets, Insurance, Banking, Wealth | 4.9 |
| 4 | Innowise | Neobank & cloud banking systems | 2007 | 3,500+ | SMEs & Enterprises | Digital Banking, LendTech, InsurTech, Investment | 4.8 |
| 5 | Netguru | Digital banking, BaaS APIs & Open Banking | 2008 | 700+ | Startups & SMEs | Digital Banking, WealthTech, Payments, BaaS | 4.8 |
| 6 | Miquido | Mobile banking & AI-powered financial products | 2011 | 250–999 | Startups & SMEs | Digital Banking, InsurTech, LendTech, Payments | 4.9 |
| 7 | Cleveroad | Native mobile fintech with AI/ML integration | 2011 | 250–999 | Startups & SMEs | Payments, Digital Banking, LendTech, InsurTech | 4.8 |
| 8 | Itexus | Finance-degree analysts embedded in teams | 2013 | 100–249 | Startups & SMEs | Digital Banking, WealthTech, Payments, Neobanking | 4.9 |
| 9 | SDK.finance | Licensed fintech source code for fast deployment | 2013 | 50–249 | Startups & SMEs | Payments, Digital Banking, eWallet, Remittance | 4.9 |
| 10 | Empat | KYC/AML systems, wallets & payment infrastructure | 2013 | 250–999 | Startups & SMEs | Fintech, HealthTech, EdTech, PropTech | 4.9 |
| 11 | Nimble AppGenie | Fintech MVPs, blockchain & AI wallets | 2017 | 50–249 | Startups & SMEs | Payments, Digital Banking, eWallet, Blockchain | 5.0 |
| 12 | 10Pearls | Enterprise fintech & AI/data-driven products | 2004 | 1,000+ | SMEs & Enterprises | LendTech, Payments, Digital Banking | 4.8 |
| 13 | Intellectsoft | Crypto wallets, trading systems, IS360 delivery | 2007 | 250–999 | SMEs & Enterprises | Payments, Crypto, Digital Banking, Investment | 4.8 |
| 14 | Andersen Inc. | Large-scale enterprise financial software | 2007 | 1,000+ | Enterprises | Banking, Investment, Insurance | 4.8 |
| 15 | KindGeek | White-label neobanks, GPT assistants & Web3 | 2014 | 100–249 | Startups & SMEs | Neobanking, Payments, LendTech, PFM | 5.0 |
| 16 | Django Stars | Lending, payments & WealthTech since 2008 | 2008 | 100–249 | Startups & SMEs | Payments, LendTech, WealthTech, RegTech | 4.9 |
| 17 | Inoxoft | Big data & AI for credit and risk platforms | 2014 | 100–249 | Startups & SMEs | Digital Banking, LendTech, InsurTech | 4.9 |
| 18 | SPD Technology | Fintech engineering with long UK track record | 2005 | 250–999 | SMEs & Enterprises | Payments, Digital Banking, InsurTech, WealthTech | 4.9 |
| 19 | GeekyAnts | React/Flutter fintech apps & generative AI | 2006 | 250–999 | Startups & SMEs | Fintech, SaaS, Payments, Digital Banking | 4.8 |
| 20 | Surf | Mobile-first fintech (iOS, Android, Flutter) | 2011 | 250–999 | SMEs & Enterprises | Digital Banking, Payments, Personal Finance | 4.8 |
Finding the best fintech mobile app development company in the UK is not something you settle in seconds. This list should make the first cut a lot easier. If your project is a general mobile build rather than a regulated financial product, our list of the top mobile app development companies in UK is the better starting point.
Not sure which company fits you?
Send us your shortlist. We will point out the three best fits, even if we are not one of them.
Get my free shortlist reviewTop 20 Fintech App Development Companies in UK
1. Brain Station 23
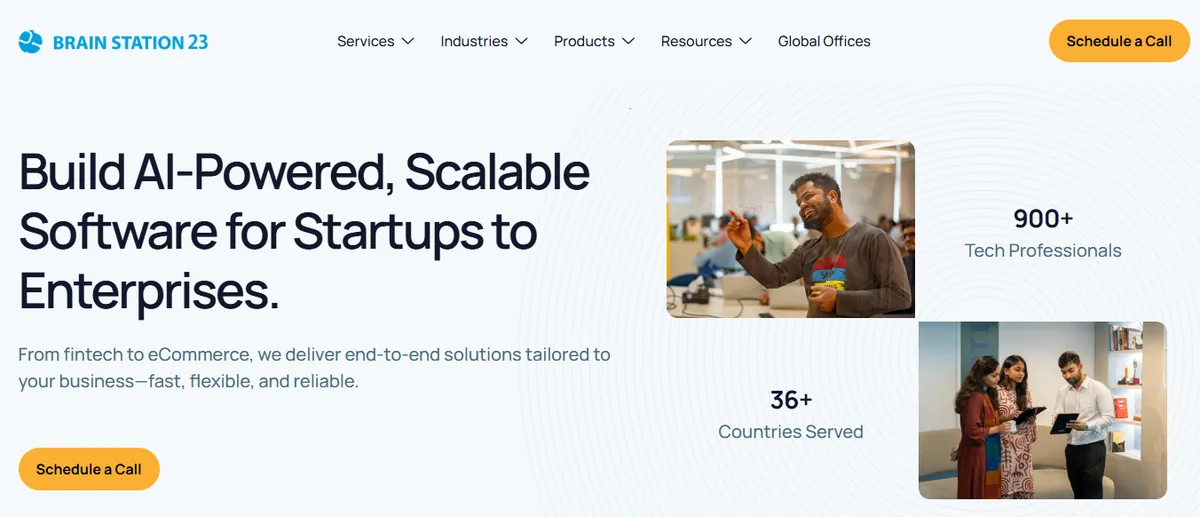
There’s a way to shorten your search: Brain Station 23.
Founded in 2006, Brain Station 23 has spent two decades building some of the most technically demanding fintech products on the market. Cross-border remittance platforms, digital wallets, AI-powered banking infrastructure and real-time payment systems are all part of its delivery record.
More than 12 million engineering hours and a team of 900+ engineers have shipped work across fintech, telecom, healthcare, SaaS and retail in 36+ countries.
What puts Brain Station 23 among the top fintech app development companies in UK is not its 4.9 Clutch rating alone. It is proven fintech expertise across both consumer-facing apps and complex backend financial infrastructure, backed by ISO 27001, ISO 9001, SOC 2 Type II and CMMI Level 3 credentials.
Engagement runs from the first line of code through post-launch support. One honest caveat from verified Clutch reviews: a few clients said onboarding and internal coordination could have been faster in the first weeks, so agree the onboarding plan and named contacts up front.
Case study
Want to see how this works in real life?
Read how we built it for a real client: the problem, the solution and the results.
Explore case studies- Digital wallet, cross-border remittance and payment platform development
- Mobile banking app development (iOS, Android, cross-platform)
- AI and ML integration for fintech products
- API integration and third-party financial services connectivity
- App maintenance, security patching and post-launch support
- Payments
- Remittance
- Digital Banking
- FinTech SaaS
- Enterprise Finance
Year Founded: 2006
Company Size: 900+ employees
Clutch Rating: 4.9/5 (21 reviews)
Best For: Startups, SMEs and enterprises
Have a project in mind?
Let’s talk it through. You get an honest expert view in 30 minutes.
2. Appinventiv
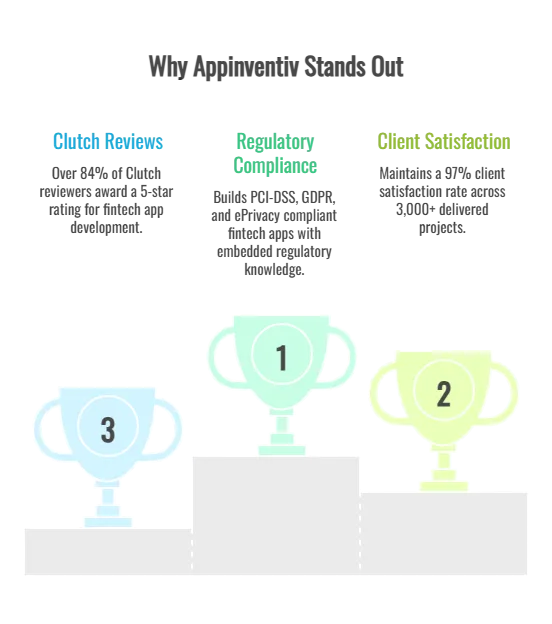
Appinventiv is known for doing exactly what it says it will do: building strong fintech apps. Its client list includes big names like KFC, Adidas and IKEA, alongside financial services clients across payments, lending and digital banking.
Core Fintech Services- Digital wallet and mobile banking app development
- AI-driven fraud detection and risk scoring systems
- Payment gateway and P2P lending platform development
- Investment and stock trading platform development
- Legacy financial system modernisation
- Payments & Digital Banking
- WealthTech
- InsurTech
- LendTech
- Retail Finance
Year Founded: 2014
Company Size: 1,600+ employees
Clutch Rating: 4.7/5 (90+ reviews)
Best For: SMEs and enterprises
3. DataArt
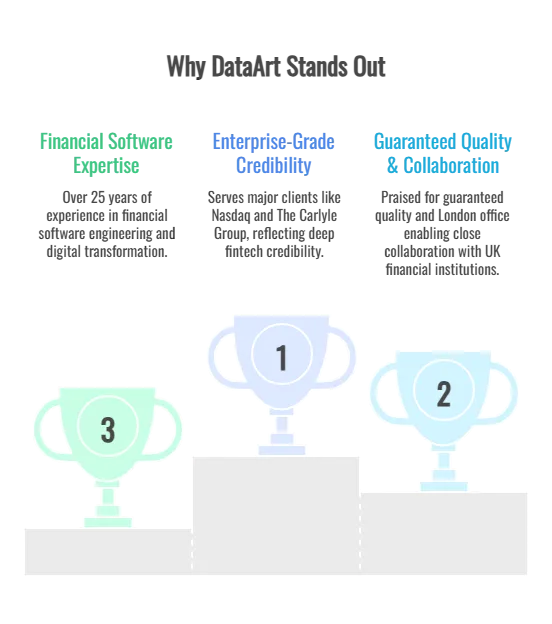
Few companies have kept financial software engineering running as smoothly as DataArt. Since 1997 it has served major clients like Nasdaq, The Carlyle Group and Betfair, which earned it a reputation as an enterprise partner. With nearly three decades behind it, DataArt has proven itself in banking, wealth management and payments, as well as capital markets and insurance.
Core Fintech Services- Core banking system modernisation and legacy re-engineering
- Data management, analytics and BI for financial services
- Insurance software development
- Cloud-native financial platform engineering
- Cybersecurity services for financial institutions
- Capital Markets
- Insurance
- Banking
- Wealth Management
- Payments
Year Founded: 1997
Company Size: 5,000+ employees
Clutch Rating: 4.9/5 (26 reviews)
Best For: Enterprises
4. Innowise
Innowise has been quietly building its fintech practice for nearly two decades. With 3,500+ engineers, it has the technical capacity and a working understanding of the regulatory environment. It is not an offshore firm learning FCA compliance on your budget, and a 93% client retention rate backs that up.
Core Fintech Services- Neobank and cloud-based banking system development
- Robo-advisory and AI-powered investment tools
- Mobile and web fintech app development
- IT staff augmentation for fintech teams
- QA automation and cybersecurity
- Digital Banking
- LendTech
- InsurTech
- Investment Platforms
- Payments
Year Founded: 2007
Company Size: 3,500+ employees
Clutch Rating: 4.8/5 (72 reviews)
Best For: SMEs and enterprises
5. Netguru
Most mobile app development companies give 10 to 20% of their service focus to fintech. Netguru has pushed that to 40%. Since 2008 it has sharpened its experience helping clients with digital banking platforms, BaaS APIs and investment tools, for clients ranging from early-stage startups to Adyen and UBS.
Core Fintech Services- Digital banking and neobank platform development
- Banking-as-a-Service (BaaS) API development
- Investment and wealth management platforms
- Fintech UX/UI design and consulting
- Open Banking integration
- Digital Banking
- WealthTech
- Payments
- BaaS
- Fintech Startups
Year Founded: 2008
Company Size: 700+ employees
Clutch Rating: 4.8/5 (51 reviews)
Best For: Startups and SMEs
6. Miquido
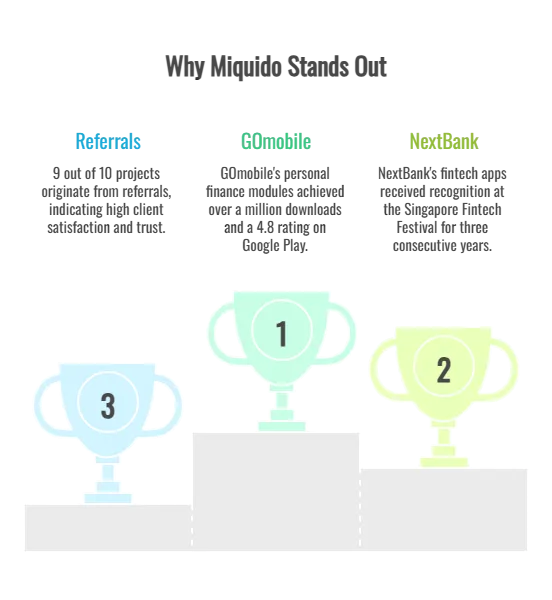
Miquido’s portfolio speaks for itself. Beyond its BNP Paribas banking modules with over a million downloads, it earned fintech recognition at the Singapore Fintech Festival three years running. Since 2011 it has built solid goodwill across digital banking, InsurTech, LendTech, personal finance and payments.
Core Fintech Services- Mobile banking and digital wallet development
- AI and ML-powered financial product development
- Insurance and lending app development
- Cross-platform fintech app development (Flutter, React Native)
- Fintech UX/UI design and product strategy
- Digital Banking
- InsurTech
- LendTech
- Personal Finance
- Payments
Year Founded: 2011
Company Size: 250–999 employees
Clutch Rating: 4.9/5 (51 reviews)
Best For: Startups and SMEs
7. Cleveroad
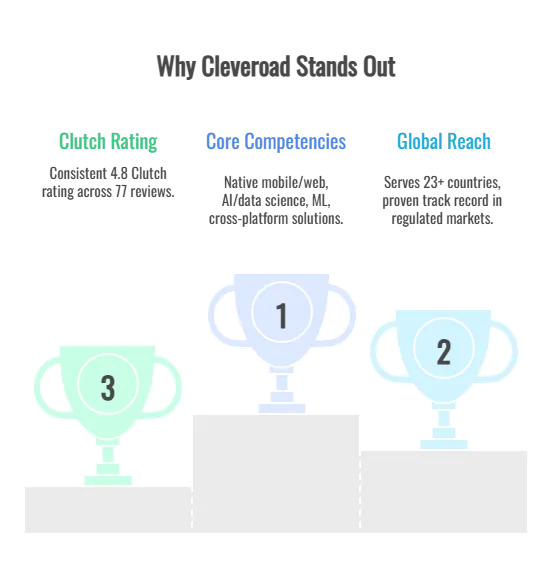
If over a decade of experience and clients in 23 countries signal a good fintech partner to you, Cleveroad is a strong match. It combines solid native mobile engineering with growing AI capability, which gives modern fintech products an edge. A 4.8 Clutch rating from 77 verified reviews says a lot about its consistency.
Core Fintech Services- Native iOS and Android fintech app development
- Cross-platform fintech solutions
- AI and machine learning integration for financial products
- Web application development for financial services
- Custom fintech consulting and UI/UX design
- Payments
- Digital Banking
- LendTech
- eCommerce Finance
- InsurTech
Year Founded: 2011
Company Size: 250–999 employees
Clutch Rating: 4.8/5 (77 reviews)
Best For: Startups and SMEs
8. Itexus
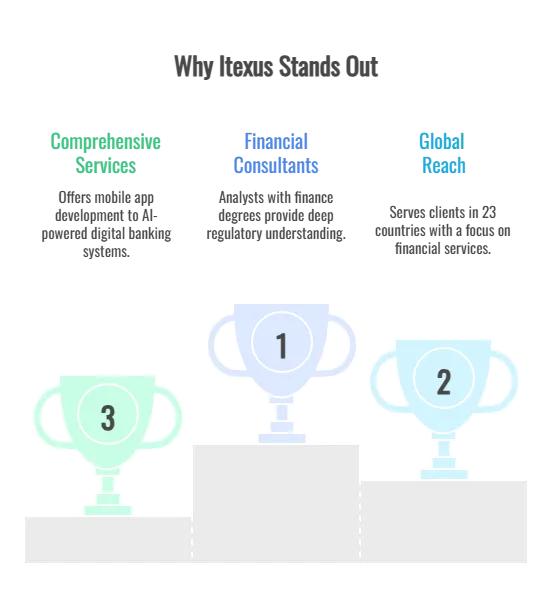
Itexus does not rely on developers alone to build fintech apps. It brings in analysts with actual finance degrees who add real domain knowledge to each project. Since 2013 it has served clients in 23 countries and drawn attention with its free pre-project analysis.
Core Fintech Services- Digital wallet and mobile banking app development
- Stock trading and investment platform development
- White-label SaaS online banking platforms
- AI-powered digital banking and risk management systems
- Fintech consulting and UI/UX design
- Digital Banking
- WealthTech
- Payments
- LendTech
- Neobanking
Year Founded: 2013
Company Size: 100–249 employees
Clutch Rating: 4.9/5
Best For: Startups and SMEs
9. SDK.finance
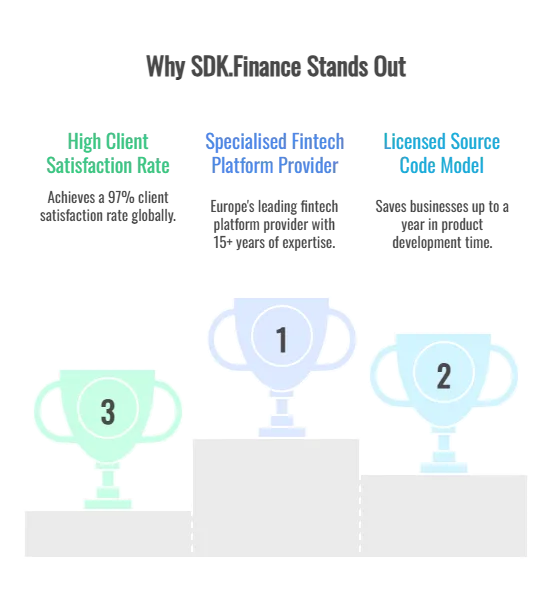
The name says how focused SDK.finance is on fintech platform development. eWallets, neobank systems, BNPL products and money remittance platforms are all in its wheelhouse. Thanks to its licensed source code model, it can deliver a production-ready platform faster than many competitors.
Core Fintech Services- White-label fintech platform development with source code licence
- eWallet, neobank and money remittance platform development
- BNPL solution development
- Loan lending and payment processing system development
- Fintech product consulting and architecture design
- Payments
- Digital Banking
- LendTech
- eWallet
- Remittance
Year Founded: 2013
Company Size: 50–249 employees
Clutch Rating: 4.9/5
Best For: Startups and SMEs
10. Empat
Since 2013, Empat has put fintech at the centre of its portfolio and backed it with full-cycle product delivery. With strong ground in compliance-heavy areas such as KYC/AML systems, payment infrastructure and digital wallets, it has held its place among the top fintech app development companies in UK for some time.
Core Fintech Services- Fintech mobile and web app development
- Digital wallet and KYC/AML solutions
- AI development for financial services
- CRM and ERP systems for financial institutions
- Product research and go-to-market support
- Fintech
- HealthTech
- EdTech
- PropTech
- Retail & eCommerce
Year Founded: 2013
Company Size: 250–999 employees
Clutch Rating: 4.9/5
Best For: Startups and SMEs
11. Nimble AppGenie
One of the youngest companies on this list, Nimble AppGenie has surprisingly strong review scores. A 5.0 Clutch rating from 19 verified reviews shows that age does not define competence. ISO 9001:2015 certification and AWS Partner status give it extra credibility with fintech buyers.
Core Fintech Services- eWallet and mobile banking app development
- BNPL and loan lending platform development
- AI and blockchain-powered fintech solutions
- Cross-platform fintech app development
- Fintech MVP development and consulting
- Payments
- Digital Banking
- LendTech
- eWallet
- Blockchain Finance
Year Founded: 2017
Company Size: 50–249 employees
Clutch Rating: 5.0/5 (19 reviews)
Best For: Startups and SMEs

12. 10Pearls
In business since 2004, 10Pearls has engineered fintech products that show a firm grip on both technology and regulation. Its work with BillGO, Galileo and Corcentric shows how well it understands financial infrastructure. It knows how to raise codebase quality while cutting security vulnerabilities at the same time.
Core Fintech Services- AI and machine learning-powered fintech product development
- Custom fintech software development (MEAN stack and cloud-native)
- Data science and analytics for financial services
- Auto lending and credit platform development
- Digital transformation for traditional financial institutions
- LendTech
- Payments
- Digital Banking
- Enterprise Finance
- InsurTech
Year Founded: 2004
Company Size: 1,000+ employees
Clutch Rating: 4.8/5 (36 reviews)
Best For: SMEs and enterprises
13. Intellectsoft
Strong fintech products, the IS360 delivery framework and nearly two decades of experience add up to Intellectsoft. It is better known as a long-term partner than a short-term vendor, a reputation earned through the crypto wallets, trading systems and cross-border payment infrastructure it has built.
Core Fintech Services- Digital wallet and crypto wallet development
- Secure trading and payment processing platform development
- Cross-border transaction and lending system development
- Full lifecycle custom fintech software management
- IT staff augmentation for fintech engineering teams
- Payments
- Crypto & Blockchain
- Digital Banking
- Investment
- InsurTech
Year Founded: 2007
Company Size: 250–999 employees
Clutch Rating: 4.8/5 (42 reviews)
Best For: SMEs and enterprises
14. Andersen Inc.
Andersen has repeatedly delivered for UK businesses with no room for error. With 1,000+ engineers across multiple delivery centres, it has the depth needed for complex financial software, which is why companies like Siemens, S&P Global and IHS Markit appear on its client list.
Core Fintech Services- FinTech, banking, investment and insurance software development
- Business process automation for financial institutions
- Custom software development and system integration
- IT staff augmentation for large financial engineering teams
- QA and testing services for regulated fintech products
- Banking
- Investment
- Insurance
- Financial Services
- Enterprise Finance
Year Founded: 2007
Company Size: 1,000+ employees
Clutch Rating: 4.8/5 (129 reviews)
Best For: Enterprises
15. KindGeek
A perfect 5.0 Clutch rating across 29 reviews is a strong reason for KindGeek to be on this list. From neobank platforms and GPT-powered financial assistants to Web3 fintech products, it handles a wide range of builds. Its pre-built white-label products help UK startups go from idea to launch much faster.
Core Fintech Services- White-label neobank and core payments platform development
- GPT-powered AI assistant integration for financial products
- Digital wallet and invoicing tool development
- Fintech SaaS platform development
- Blockchain and Web3 financial solution development
- Neobanking
- Payments
- LendTech
- Personal Finance Management
- Blockchain Finance
Year Founded: 2014
Company Size: 100–249 employees
Clutch Rating: 5.0/5 (29 reviews)
Best For: Startups and SMEs
16. Django Stars
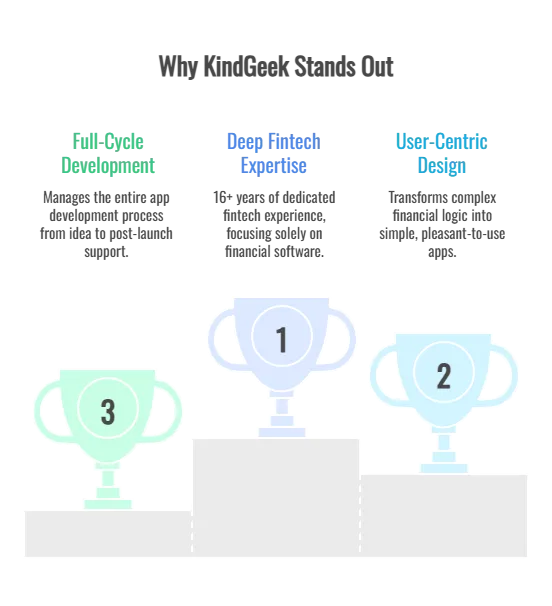
Django Stars has spent more than 18 years building financial software. It has touched almost every area a fintech product relates to, from lending platforms and wealth management tools to payment integrations and high-load financial backends.
Core Fintech Services- Payment integration and processing platform development
- Lending platform and wealth management tool development
- Full-cycle fintech product development (ideation to post-launch)
- Regulatory compliance and KYC integration
- Backend architecture for high-load financial systems
- Payments
- LendTech
- WealthTech
- RegTech
- Fintech Startups
Year Founded: 2008
Company Size: 100–249 employees
Clutch Rating: 4.9/5
Best For: Startups and SMEs
17. Inoxoft
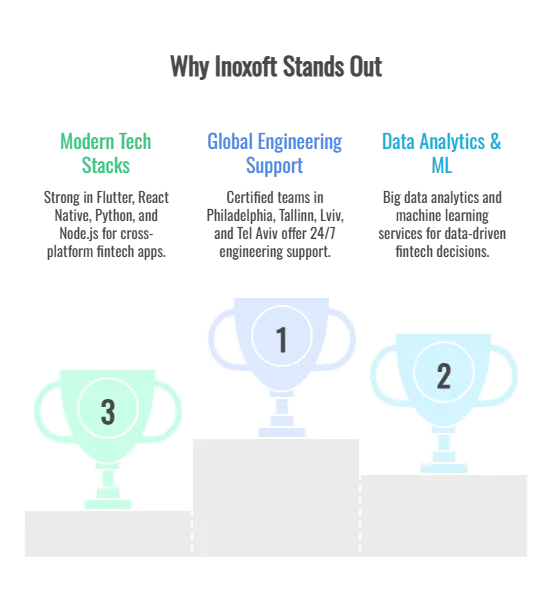
If you want a practical, cross-continental approach to your next fintech build, Inoxoft is worth a call. Its focus on big data analytics and AI decision-making shows in the credit scoring engines, risk management platforms and data-heavy investment tools it builds.
Core Fintech Services- Custom fintech app development (Flutter, React Native, Python, .NET)
- Big data analytics and machine learning for financial services
- AI-driven decision-making tools for financial institutions
- Cloud integration and DevOps for fintech products
- Mobile and web fintech application development
- Digital Banking
- LendTech
- InsurTech
- Investment Platforms
- Payments
Year Founded: 2014
Company Size: 100–249 employees
Clutch Rating: 4.9/5
Best For: Startups and SMEs
18. SPD Technology
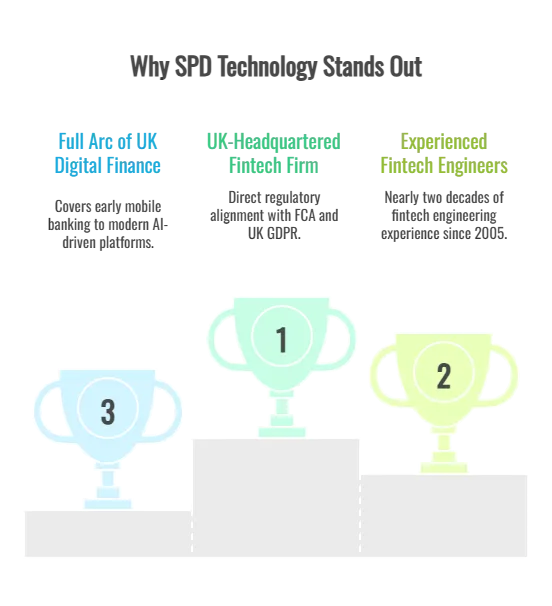
Few companies understand FCA expectations like SPD Technology. It has spent two decades building fintech products that meet the standards of British financial institutions.
Core Fintech Services- Full-cycle fintech product engineering
- Mobile and web fintech app development
- AI/ML integration for financial services
- Cloud and DevOps for regulated financial platforms
- QA and security testing for fintech products
- Payments
- Digital Banking
- InsurTech
- WealthTech
- Enterprise Finance
Year Founded: 2005
Company Size: 250–999 employees
Best For: SMEs and enterprises
19. GeekyAnts
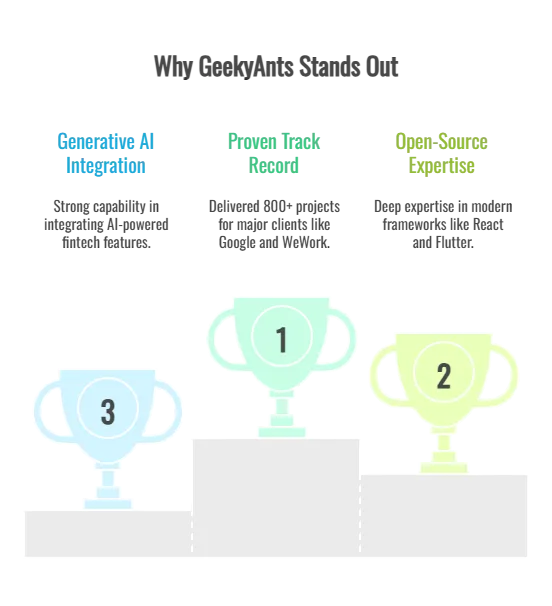
A company serving clients like Google, WeWork and ICICI Securities is operating at a serious level. Deep React, React Native and Flutter skills plus a growing generative AI practice make GeekyAnts a sound option for many UK fintech businesses.
Core Fintech Services- Mobile fintech app development (React Native, Flutter, Next.js)
- Generative AI integration for financial services
- Enterprise fintech modernisation and DevOps
- Digital product strategy and UI/UX design for fintech
- Web and mobile fintech platform development
- Fintech
- Enterprise & SaaS
- Payments
- Digital Banking
- Retail Finance
Year Founded: 2006
Company Size: 250–999 employees
Clutch Rating: 4.8/5
Best For: Startups and SMEs
20. Surf
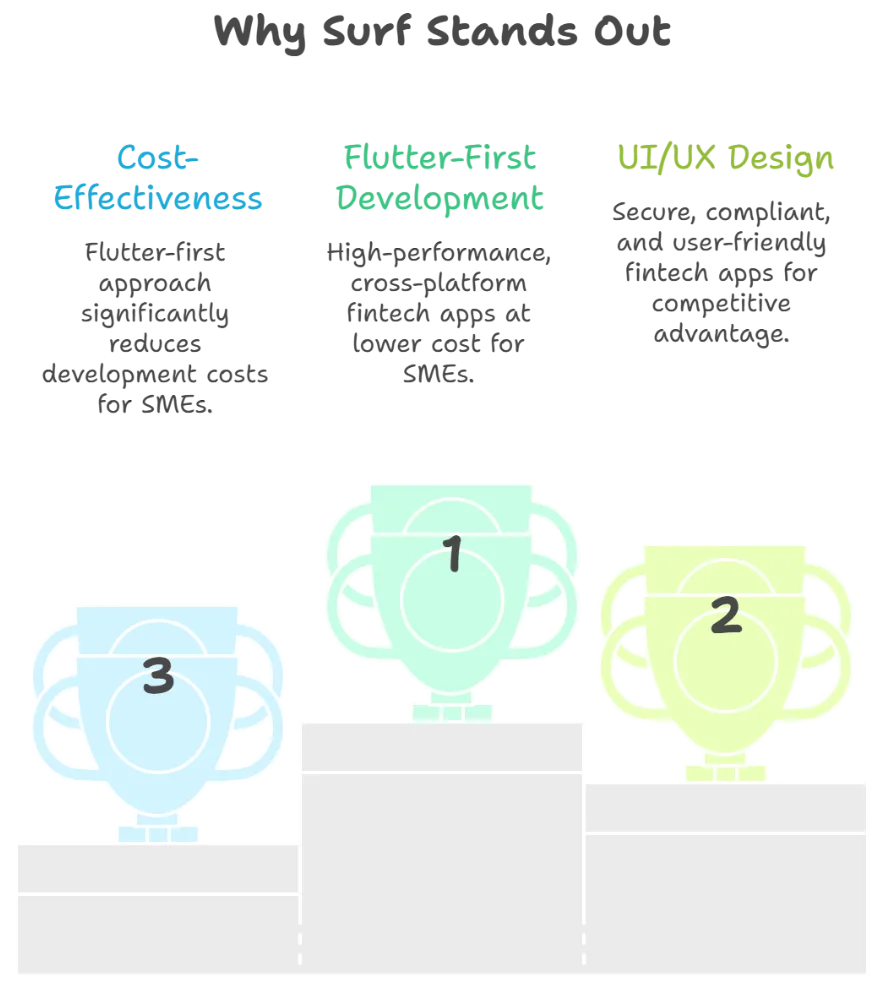
Surf has earned its reputation as a mobile-first fintech specialist. With iOS, Android and Flutter financial apps, it serves companies working in digital banking, payments and personal finance. Its post-launch support model makes it a good fit for UK fintech businesses that plan for the long term.
Core Fintech Services- Mobile fintech app development (iOS, Android, Flutter)
- Digital banking and payment platform development
- Custom fintech UI/UX design
- Backend development for financial applications
- Long-term fintech product support and scaling
- Digital Banking
- Payments
- Personal Finance
- InsurTech
- Retail Finance
Year Founded: 2011
Company Size: 250–999 employees
Clutch Rating: 4.8/5
Best For: SMEs
Brain Station 23
Your next step
Ready to pick the right partner?
Tell us what you are building. In 30 minutes you will know the next step, the rough cost and who should build it, even if it is not us.
Book my free 30-minute call- 20+ years
- 900+ engineers
- 36+ countries
- CMMI Level 3
- ISO 27001
- SOC 2 Type II
Why UK Businesses Are Investing in Fintech Apps
The UK does not follow global fintech trends. It sets them, and London has been called Europe’s fintech capital for years. So what is pushing UK businesses toward fintech app development? Six things in particular.

Open Banking Has Crossed the Tipping Point
Open Banking in the UK is no longer an innovation. It is infrastructure. By December 2025 it had reached 16.5 million user connections, a 36% rise in a year, and 351 million payments across 2025, up 57%.
For UK fintech businesses, that is less a trend than a mandate. A fintech app that does not connect to Open Banking APIs is no longer on customers’ wish list.
Neobanks Have Reset Consumer Expectations
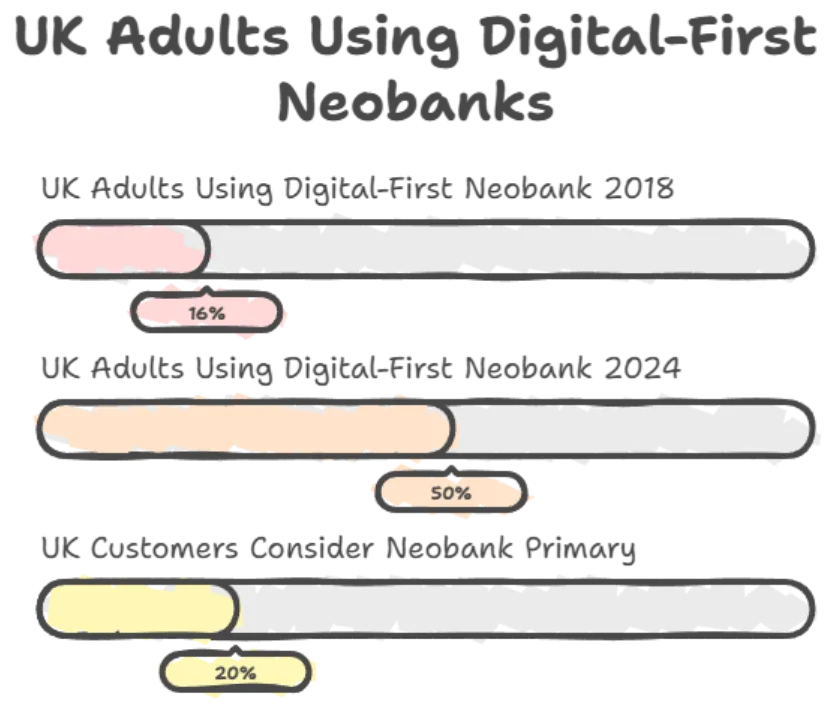
Traditional banks no longer set the standard for the banking experience. Neobanks do. Almost half of UK adults (49%) now hold a digital-only bank account, up from 40% in 2025 and 36% in 2024.
So whether you operate in retail, insurance, logistics or healthcare, your customers now expect app-led financial experiences. If you are building one, see how digital banking platforms are put together before you scope features.
Consumers Now Expect Payments to Be Instant
Next-day transfers are no longer acceptable. The Faster Payments Service processed 5.5 billion payments worth £4.8 trillion in 2025, up 9% on 2024.
UK businesses now treat payment speed as a must-have UX feature rather than a backend detail. However polished the interface, it means nothing if transactions cannot complete in seconds.

Regulation Is Both Pressure and Opportunity
The FCA does not only protect customers. It shapes markets. When a UK business gets compliance right, it avoids penalties and earns genuine trust for its product.
In 2025 the FCA launched an AI Live Testing service, where firms can trial consumer-facing AI models with regulatory support. The regulator is not constraining innovation; it is actively enabling it.
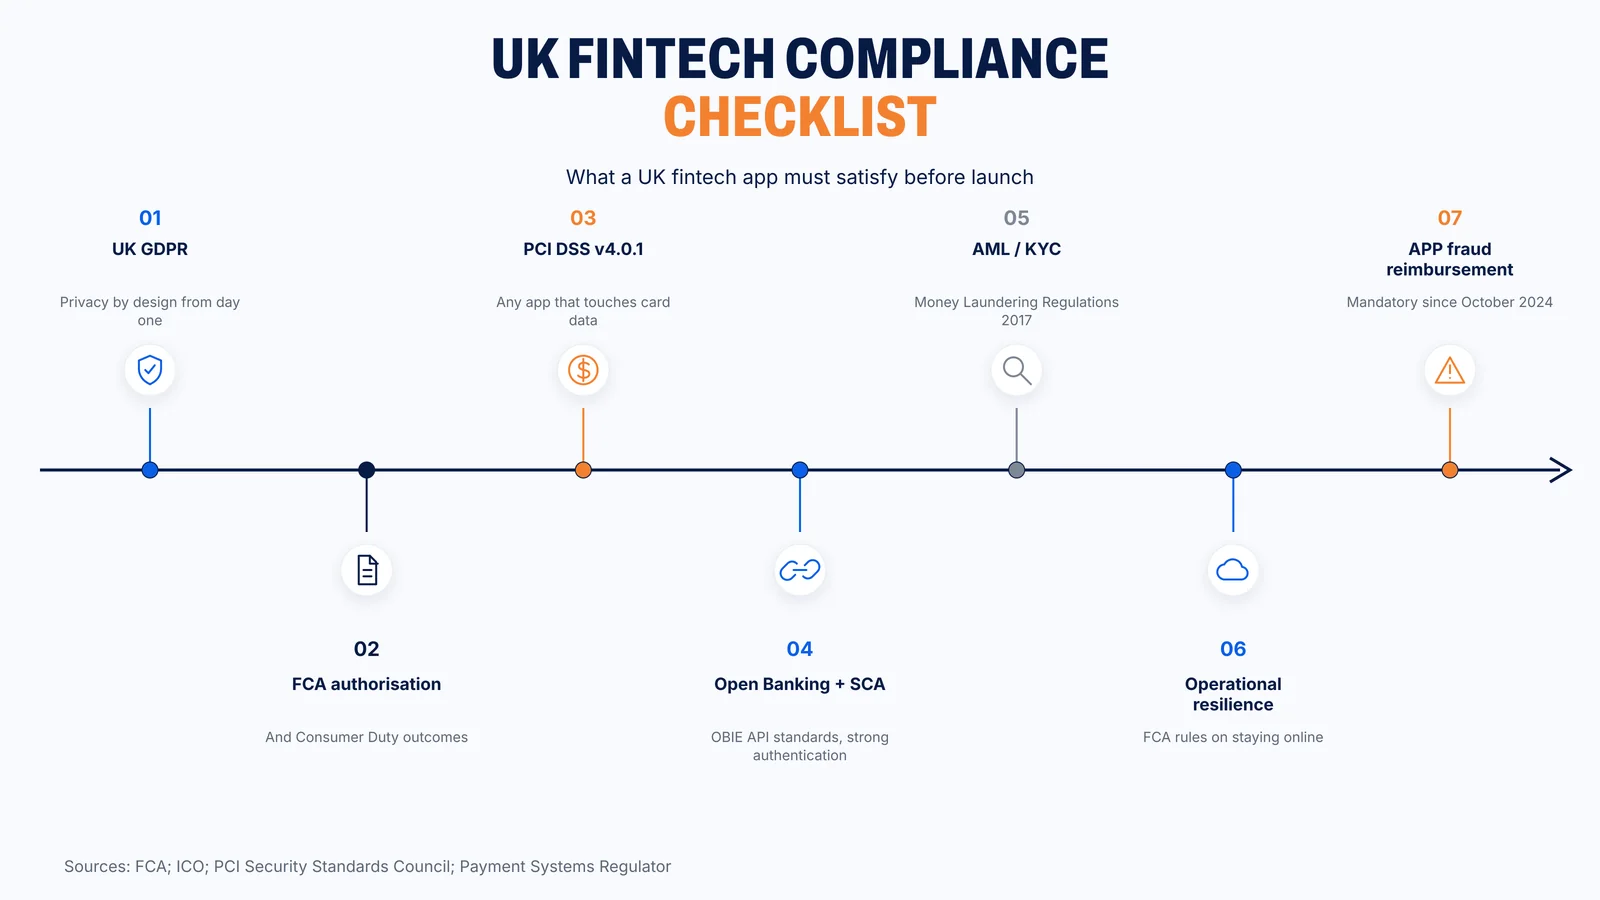
The technical compliance bar stays high, though: UK GDPR, PCI DSS, the FCA’s operational resilience rules and mandatory APP fraud reimbursement all apply. UK businesses that pick a development partner without regulatory expertise can see things go wrong quickly.

AI Is Making Financial Apps Genuinely Smarter
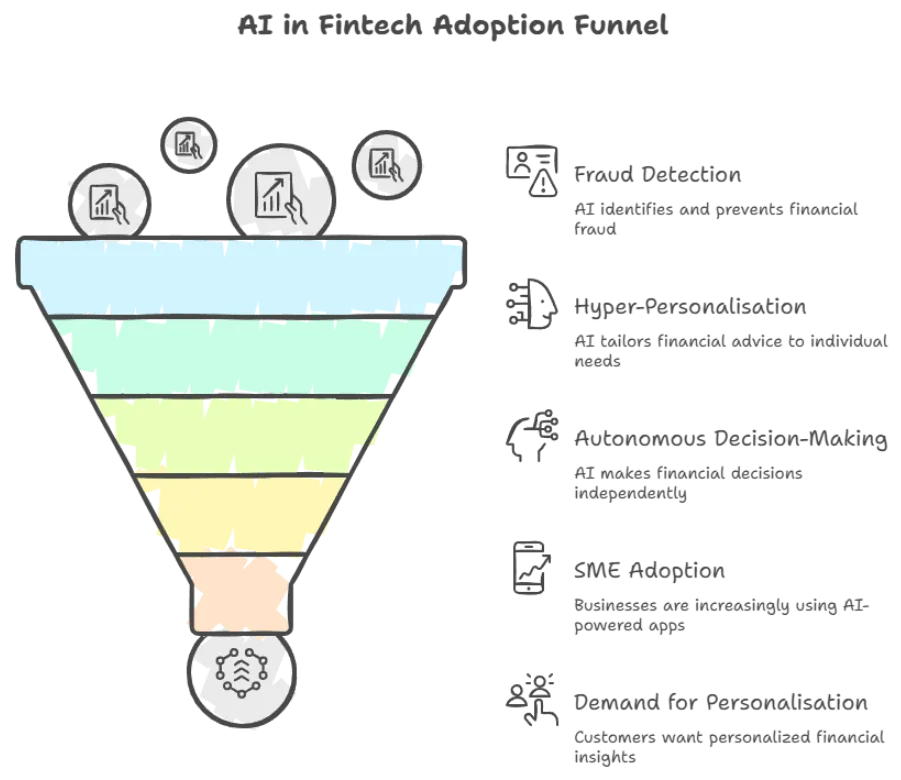
Fintech apps no longer just tell you what happened to your money. They tell you what to do with it. Fraud detection, hyper-personalisation and autonomous decision-making are now firmly on feature lists. The global AI in fintech market was valued at USD 17.64 billion in 2025 and is forecast to reach USD 97.70 billion by 2034.
That is why UK businesses are investing in AI and machine learning development for their fintech apps: users want custom recommendations and predictive insights that understand their specific context.
Cross-Border and Embedded Finance Are Rewriting the Rules
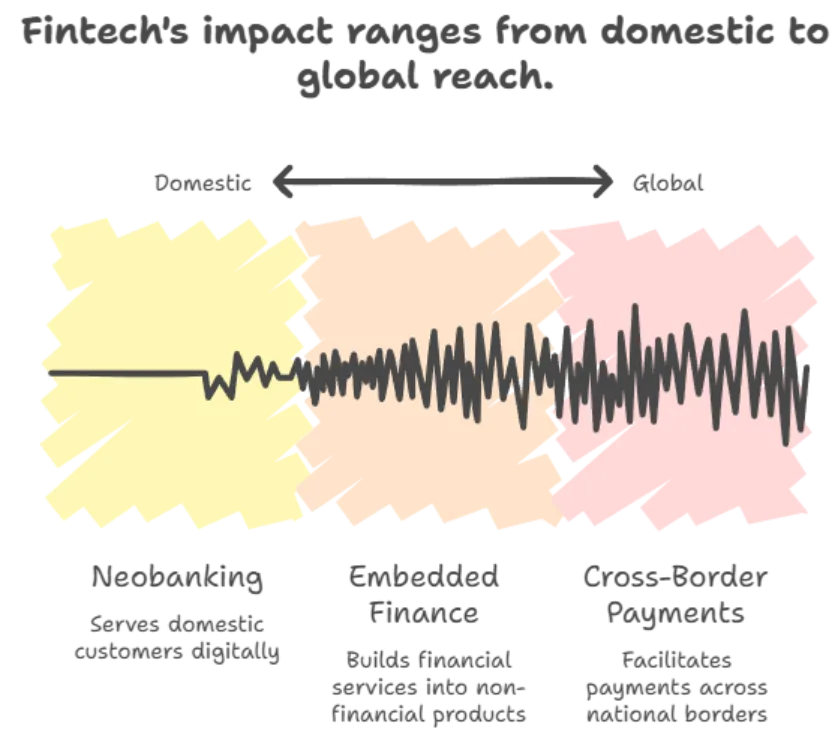
There is a big fintech opportunity for UK businesses: not just serving customers better, but following their money around the globe.
The global cross-border payments market was worth USD 194.6 trillion in 2024 and is forecast to reach USD 320 trillion by 2032. A purpose-built cross-border payments solution is now a realistic product line, not just a bank’s job.
Embedded finance is changing how businesses monetise customer relationships too, and neobanking is the UK’s fastest-growing fintech segment at a 19.18% CAGR through 2031. UK businesses that ignore fintech app development risk falling behind in retail, logistics, healthcare and beyond.
Regulatory & Compliance: The Challenges for Fintech Apps in UK
Building a fintech app is not only a development challenge. It is a legal one too. The UK has one of the most rigorous financial regulatory environments in the world, and for good reason: consumers trust fintech apps with their money and their most sensitive data. So what do fintech apps in the UK have to clear first?
UK GDPR (Your Data Handling Has to Be Airtight)
The UK left the EU but kept GDPR. Fintech organisations, whether controllers, joint controllers or processors, have distinct obligations for handling, storing and sharing personal data.

For fintech apps this is critical. You are not just holding names and email addresses. You hold transaction histories, credit behaviour, payment credentials and sometimes biometric data.
Fintech business models often combine traditional finance with third-party platforms, so meeting UK GDPR alongside sector-specific rules is not an isolated requirement.
Serious breaches can bring fines of up to £17.5 million or 4% of annual worldwide turnover, whichever is higher. The reputational fallout is worse, and in fintech, once trust is gone, everything goes with it.
What to check in your dev partner: Ask whether they build privacy by design into the architecture from the start. It cannot be a post-launch patch. A partner who knows data minimisation, lawful processing bases and breach notification duties is the right fit.
FCA Authorisation (You Can’t Skip This Queue)
The Financial Conduct Authority oversees electronic money institutions, payment firms, investment platforms and crowdfunding portals. If you move money, initiate payments, hold funds or offer financial products, FCA authorisation is unavoidable.
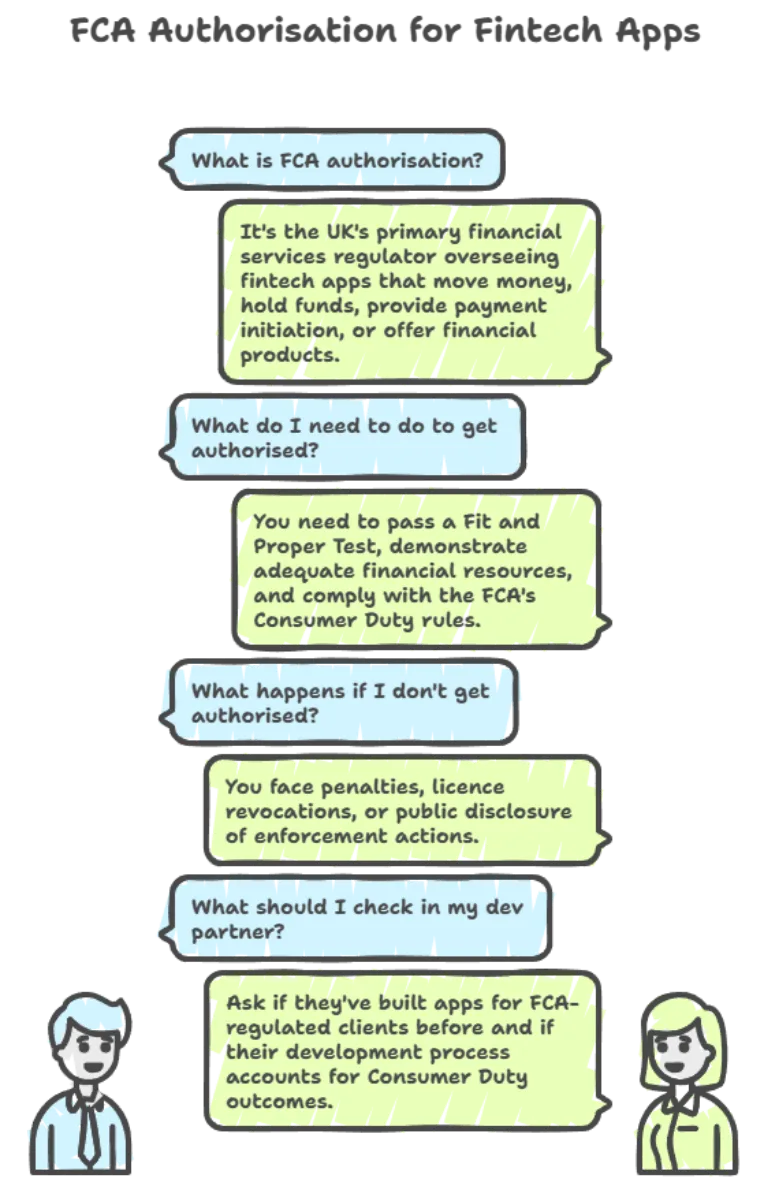
Under Consumer Duty you must show the FCA you act in customers’ best interests. The question has shifted from “what we told users” to “how our product actually affects them”. Get this wrong and the outcomes range from penalties to licence revocation to public enforcement notices.
What to check in your dev partner: You apply for the FCA licence, not your developer, but they must clearly understand what authorisation requires architecturally.
PCI DSS (Non-Negotiable for Any App That Touches Payments)
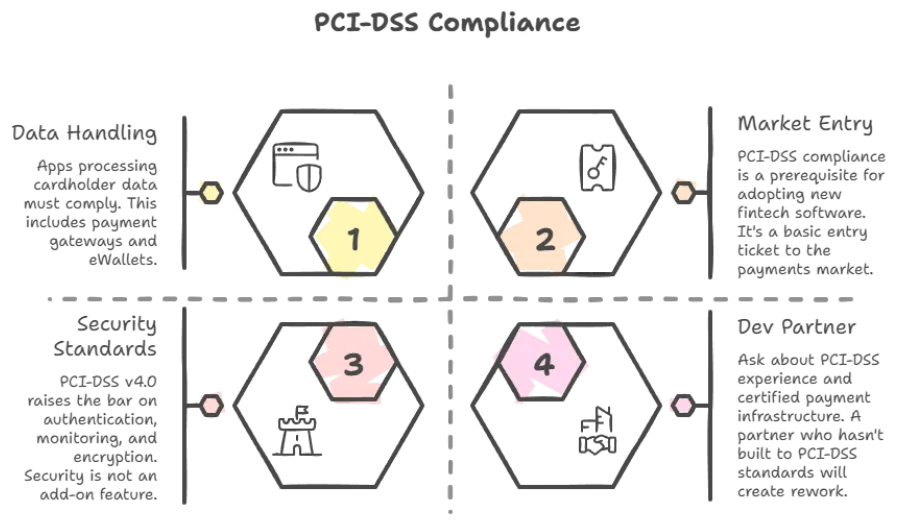
Does your app process, store or transmit cardholder data, from payment gateways to eWallets? Then PCI DSS compliance is mandatory. Banks, payment processors and major enterprises expect it from any new fintech software they integrate.
The current version, PCI DSS v4.0.1, raised the bar on continuous monitoring, authentication controls and encryption, and its future-dated requirements became mandatory in March 2025. The stakes are high: the average data breach in the financial sector cost USD 5.56 million in 2025, second only to healthcare.
What to check in your dev partner: Ask whether they have delivered PCI DSS-compliant payment infrastructure before. Otherwise you may face a lot of rework later.
Open Banking / PSD2 (The Standard Your APIs Must Meet)
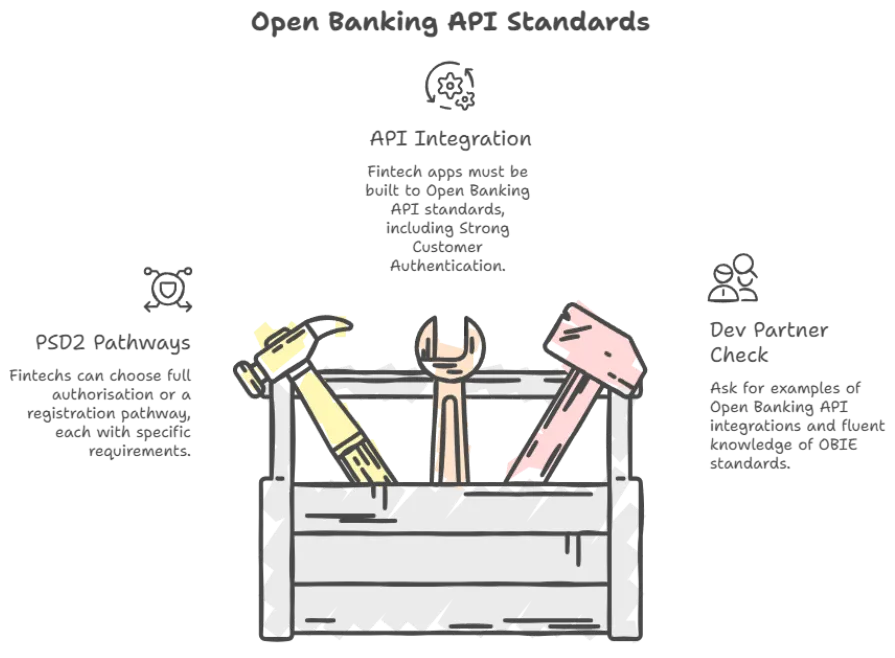
UK Open Banking is built on the PSD2 framework. Any product that touches account data, payment initiation or third-party financial integrations must be built to Open Banking API standards.
Strong Customer Authentication must also be implemented correctly for qualifying transactions. Getting it wrong is one of the most common and costly technical errors in UK fintech development.
What to check in your dev partner: Make sure they have shipped Open Banking API integrations in live products and know the OBIE standards well.
AML / KYC (The Compliance That Catches Companies Off Guard)
Many fintech businesses have stumbled on Anti-Money Laundering and Know Your Customer requirements. In 2024 the FCA fined Starling Bank £28,959,426 for financial crime failings tied to its sanctions screening. If it can happen to Starling, it can happen to anyone who treats AML as a checklist.
Before you launch, make sure your product can comply with the Money Laundering, Terrorist Financing and Transfer of Funds Regulations 2017. Digital onboarding is where most of this starts; our explainer on eKYC customer onboarding covers the basics.
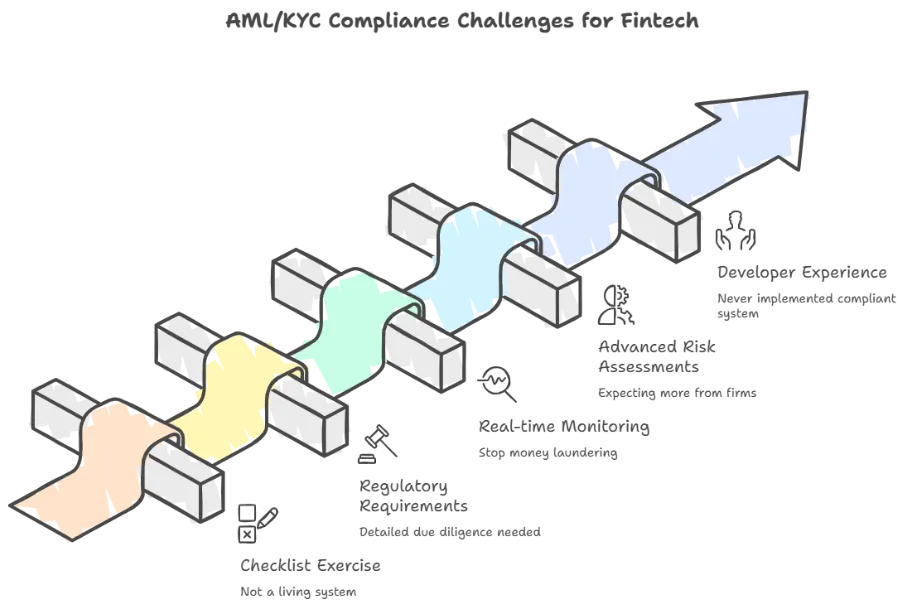
What to check in your dev partner: Even with the top fintech app development companies in UK, ask how they built KYC and AML flows in previous products. A team that has never implemented a compliant AML system is unlikely to deliver a regulated financial product.
Key Trends in UK Fintech App Development
Regulation, consumer expectations and technology all keep changing, and the UK market tends to feel those changes earlier and act faster than most. Here are the trends shaping fintech app development in the UK right now.
AI-Driven Fraud Detection
More than 444,000 cases were recorded to the UK’s National Fraud Database in 2025, a record and 6% up on 2024, which works out to over 1,200 cases a day. AI is part of the problem: 35% of UK businesses reported being targeted by AI-related fraud in Q1 2025, up from 23% a year earlier, and 68% planned to raise fraud budgets.

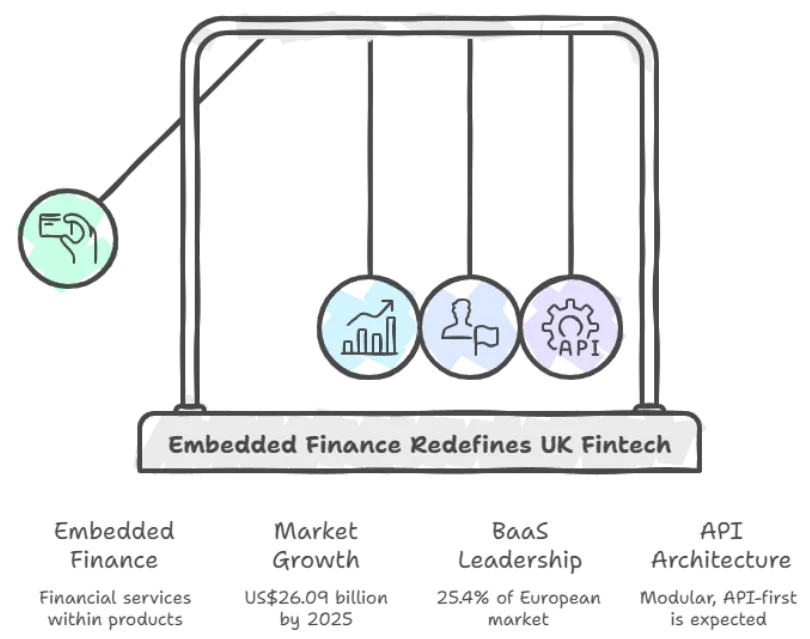
Embedded Finance and BaaS
The biggest structural shift in UK fintech is not a feature but a model. Embedded finance lets any business, without being a bank, offer financial services inside its own product.
BNPL at checkout, embedded SME lending and Open Banking payments are all growing on top of this model. Logistics firms now offer supply chain financing, retailers embed BNPL, and healthcare platforms deliver insurance products, all through fintech APIs.
Real-Time Payments
UK consumers have had Faster Payments since 2008, so anything slower now feels broken. Transaction status, payment confirmation and error handling are all expected in seconds. Real-time payment is what users want most from a UK fintech app.

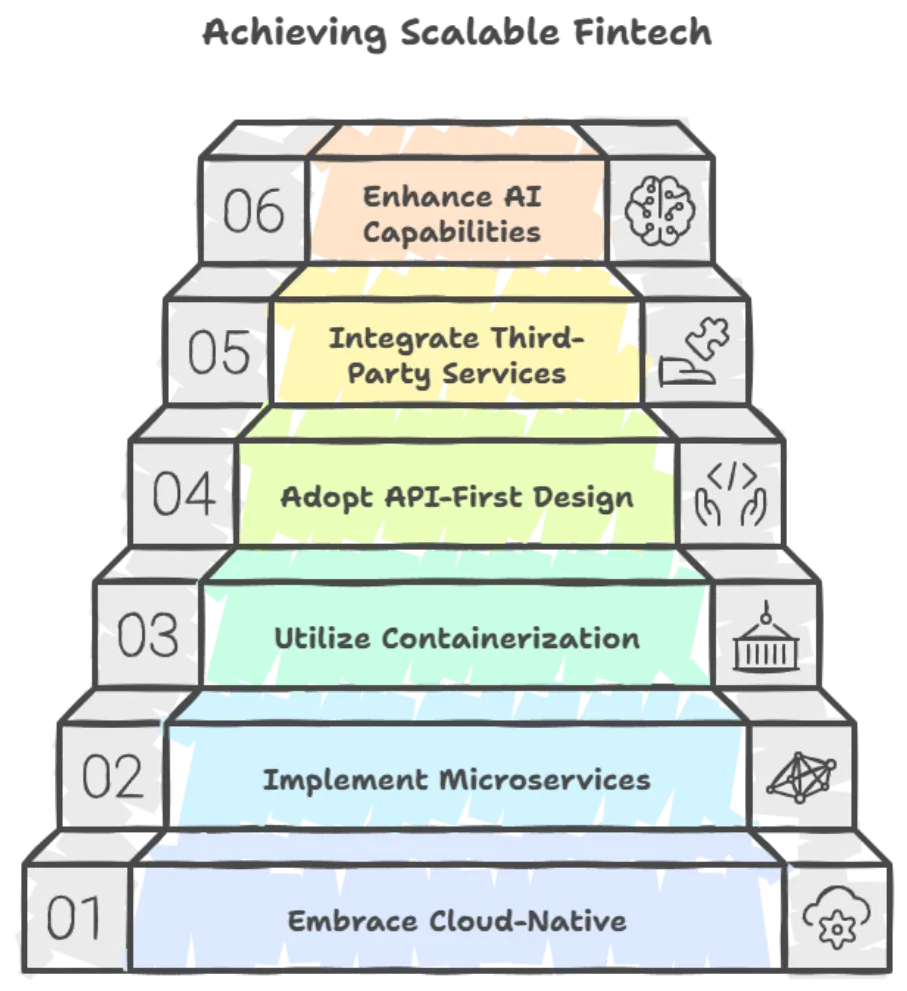
Cloud-Native Architecture
The era of on-premise financial infrastructure is nearly over. From neobanks to insurance platforms, UK fintech businesses are moving to cloud-native systems because they scale more easily, adapt faster to regulatory change and connect more cleanly to Open Banking APIs and third-party services.
Hyper-Personalisation
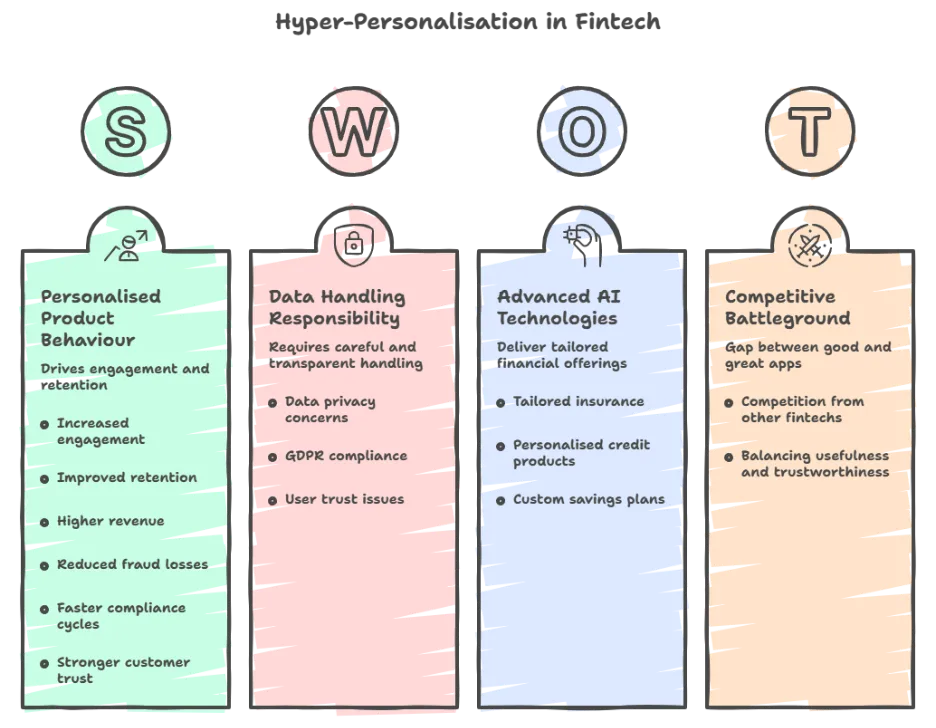
Personalisation is what separates a good fintech app from a great one. UK users no longer want an app that just manages their money; they want it to understand their behaviour. With modern AI, platforms can surface insights based on habits, send savings reminders aligned with income, and offer more relevant insurance, credit and savings products.
How We Selected the Top 20 Fintech App Development Companies in UK
Finding the best fintech app development company in the UK is not the same as finding a general app developer. Fintech brings strict regulation, real-time transactions, data security and fraud prevention. Building eCommerce or SaaS products is very different from building products under PCI DSS, FCA rules or KYC/AML requirements.
So we built this list on fintech-focused criteria only.

Fintech-Specific Portfolio and Case Studies
A reliable fintech software development company has a portfolio built around financial products. Listing fintech as one more industry on a website is not enough.
We looked for real, proven work: digital wallets, neobanking platforms, payment systems, trading apps, lending tools and insurance solutions. Case studies that show delivery capability strengthened a company’s position.
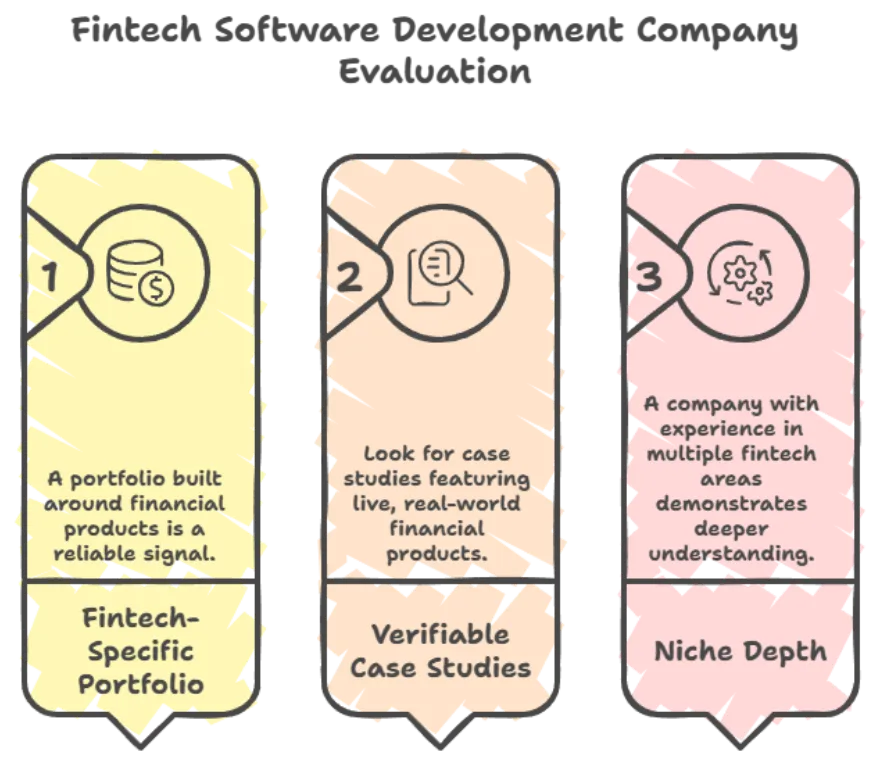
We also checked depth. A team that has built multiple payment systems understands the work better than one with a single generic project.
Security Practices and Compliance Credentials
In fintech, security is the foundation, not a feature. Many breaches now come through third-party vendors, so picking the right development partner is a security decision. Weak security puts the product, the customers, their data and sometimes regulatory approval at risk.
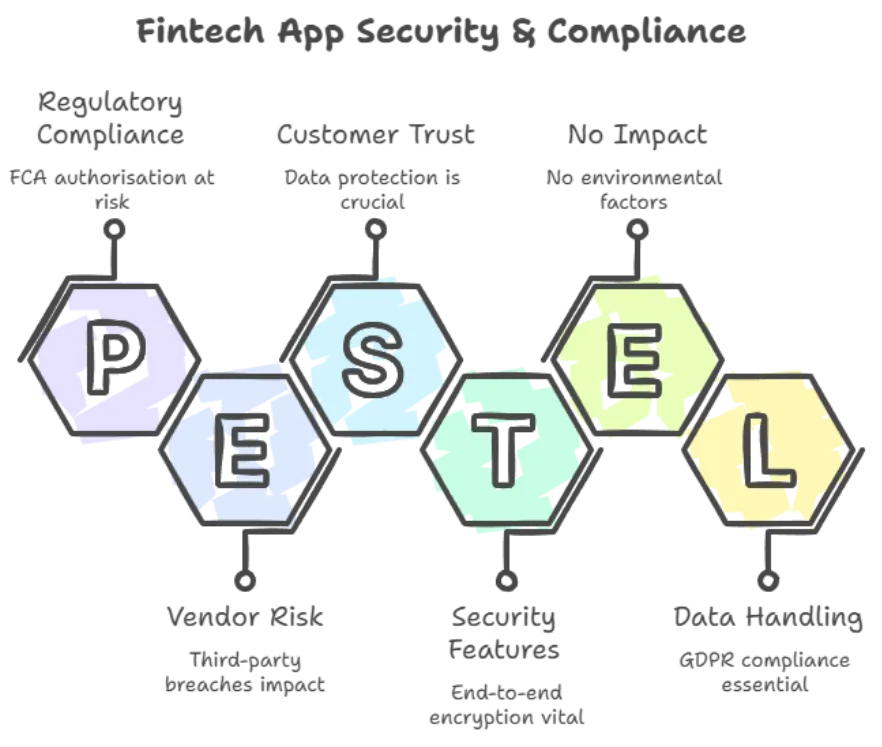
Every company on this list shows security and compliance standards such as ISO 27001, SOC 2, PCI DSS experience and GDPR practices.
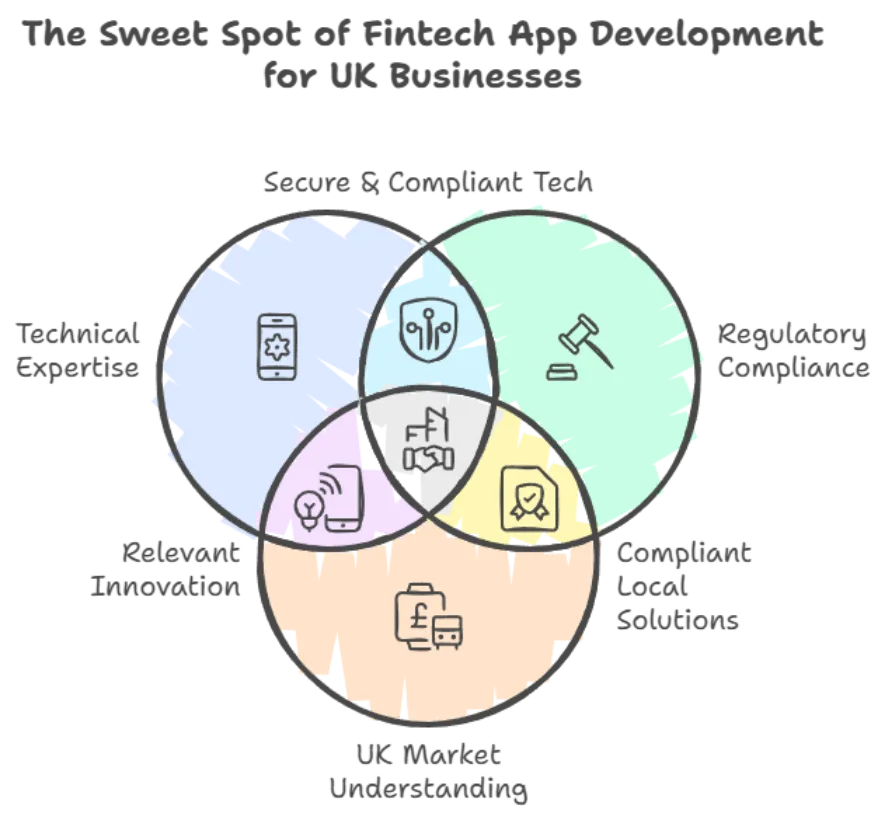
UK Market Relevance and Regulatory Awareness
The best fintech app development companies for UK buyers can be based anywhere, as long as they understand the UK’s regulatory environment. We included companies that either have a UK presence or real experience building fintech products for UK clients under FCA rules, UK GDPR, Open Banking standards and AML/KYC requirements.
Third-Party Ratings on Clutch and GoodFirms
Testimonials on a company’s own website are not the best evidence. We used Clutch and GoodFirms, where feedback is verified. Every company here had a rating of at least 4.7 out of 5 on a major review platform with a reasonable number of verified reviews.

Team Size, Structure, and Delivery Capacity
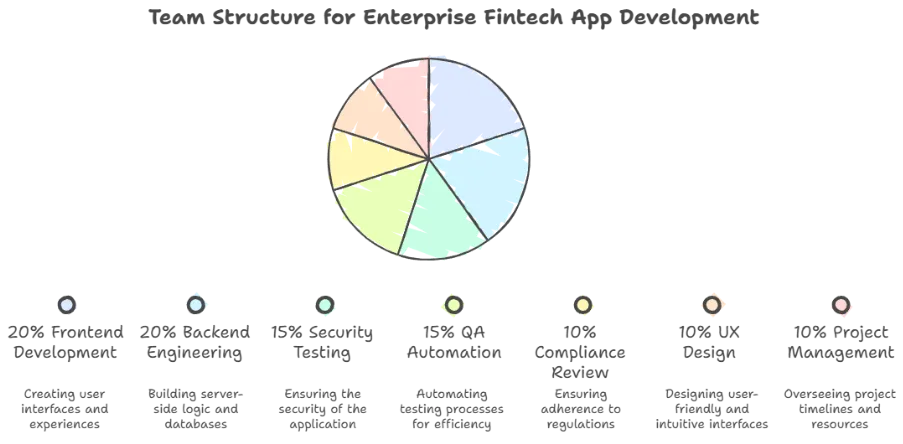
Enterprise fintech development needs frontend, backend, security, QA, compliance and UX teams working in parallel, usually on tight timelines. A small team of generalists cannot cover that, however skilled.
So every company had to have at least 50 people, including dedicated fintech engineers, QA experts, security specialists and project managers.
Post-Launch Support and Long-Term Partnership Capability
No fintech project ends at launch. Security updates, performance tuning, new regulations and changing user expectations continue for the life of the product. We picked only companies with a reputation for strong post-launch support, not teams that build and disappear.
Technology Stack and Innovation Capability
Top fintech development companies choose technologies that will stay relevant for years. We favoured teams strong in Java, Python, Node.js, Swift and Kotlin, with expertise on AWS, Azure and Google Cloud.
Cross-platform experience with Flutter and React Native mattered too, as did AI/ML capability for fraud detection, personalisation and automated decision-making.

How to Choose a Fintech App Development Company in UK
Almost every app development company will say it is the best fintech partner in the UK, with polished case studies, certifications and a confident process. But what you build will handle real money, identity and sensitive data. The risk is high, and the wrong partner makes it higher.
Use this practical checklist to find the team that can turn your fintech idea into a working product.
Step 1: Define Your Fintech Vertical Before You Talk to Anyone
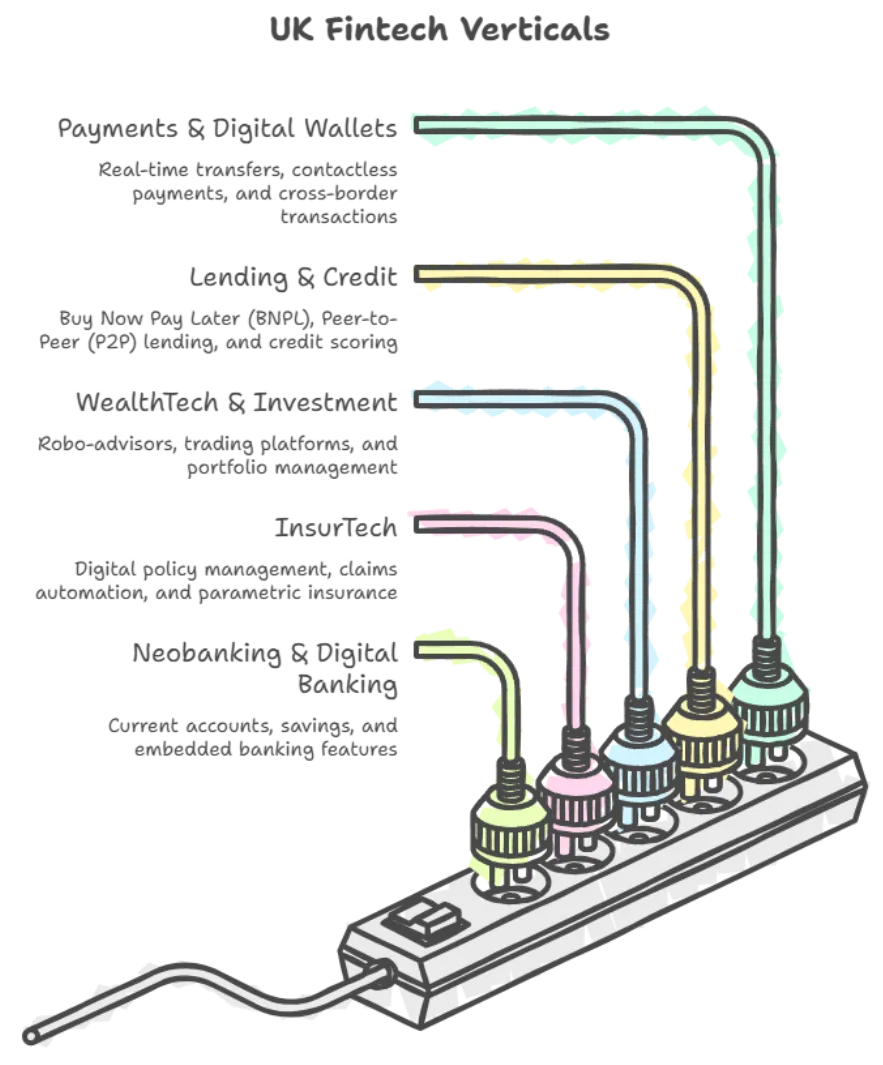
Before you call any UK fintech software development service, define exactly what you are building. “A fintech app” is not a definition. A payment gateway app, a lending platform, a robo-advisory app and an insurtech system all have different technical, regulatory and UX requirements.

Clarify your regulatory obligations, target users and expected transaction volume first. A team with neobanking expertise will not automatically understand insurtech data models, and vice versa. Once your focus is fixed, filtering out companies without relevant hands-on experience gets much easier.
Step 2: Verify Fintech-Specific Experience, Not Just General App Development
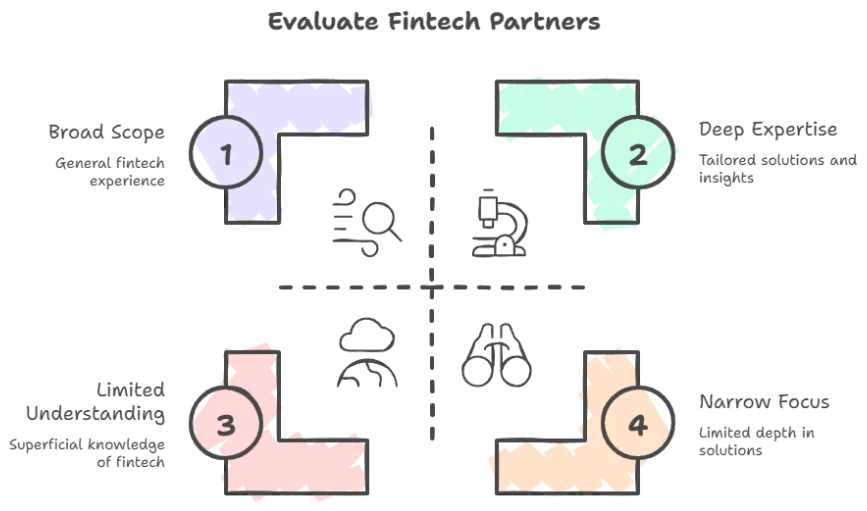
A team that builds restaurant apps and then moves into fintech is not a fintech specialist. It is experimenting in a high-risk domain, especially where compliance, payment systems and data security are concerned.
Ask for case studies in your area. Good ones explain architecture decisions, integrations and how compliance requirements were handled.
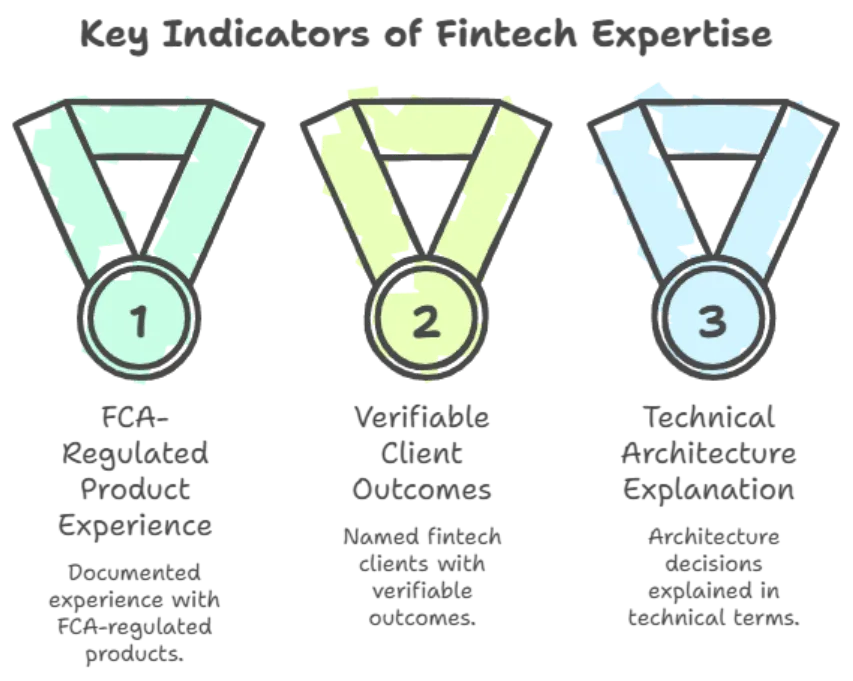
And here are the signals that should make you cautious.
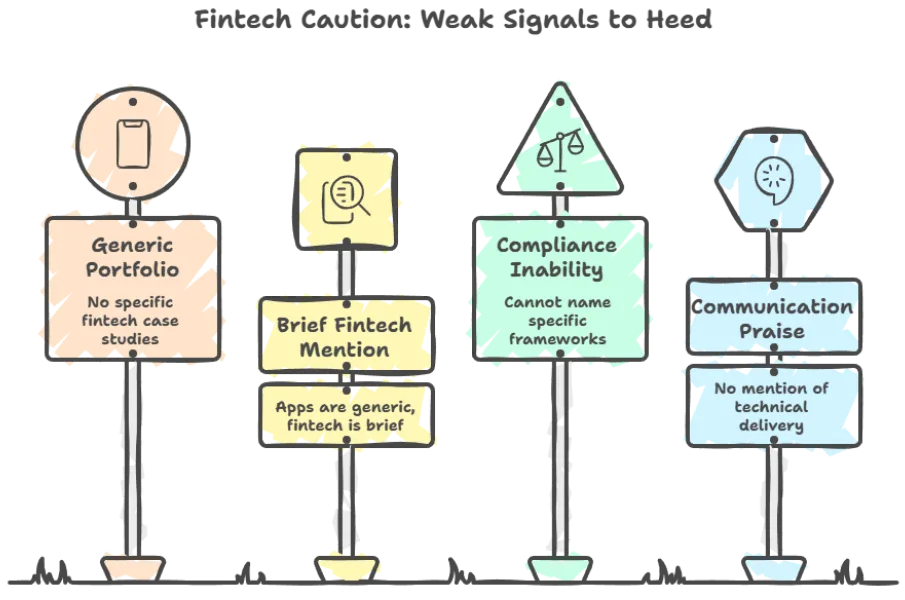
Step 3: Interrogate Their Security Architecture Before You Fall for Their Portfolio
Fintech security has to be built in from day one. Your partner must treat it as the core of the system: encryption, multi-factor authentication, biometric login, secure sessions and real-time fraud monitoring. Our cyber security services page shows the kind of controls to expect.
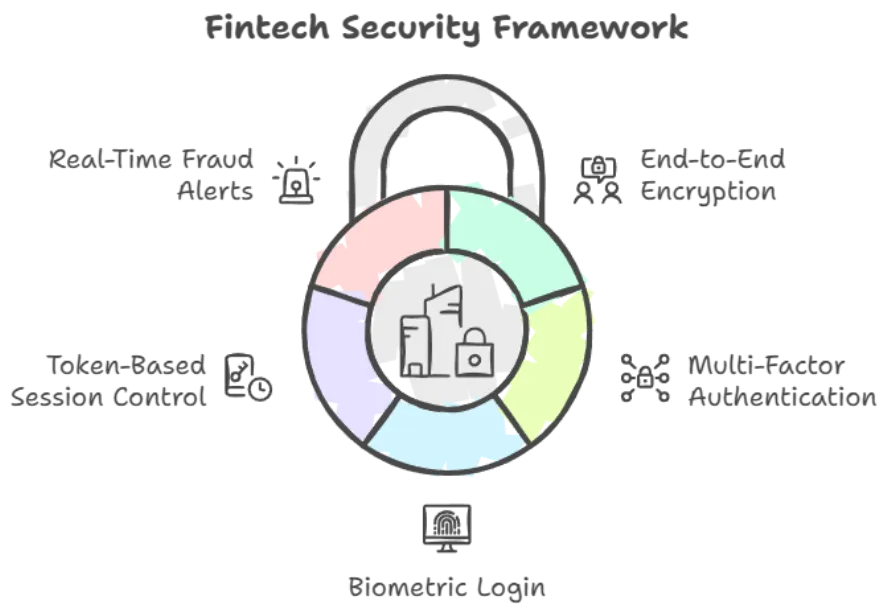
These questions reveal quickly whether a team takes security seriously:
- How do you protect data at rest and in transit?
- How do you test security, for example with penetration testing?
- Have you built PCI DSS-compliant systems before?
- How do you handle security incidents or breaches?
- Do you follow standards like ISO 27001 or SOC 2?
Clear, technical answers are a good sign. Vague ones suggest a lack of real experience.
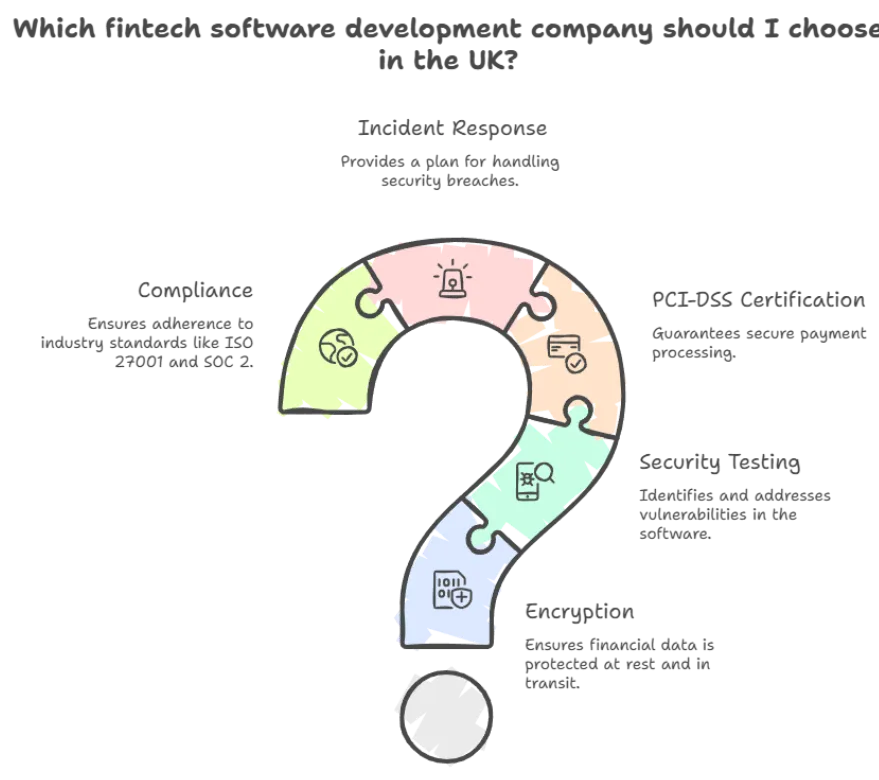
Step 4: Check Compliance Knowledge, Not Just Awareness
Knowing regulations exist and building products within them are different things. A partner without real experience of PSD2, PCI DSS, UK GDPR or FCA requirements will slow your project down. Before you hire fintech app developers in the UK, ask whether they have handled compliance in live systems.
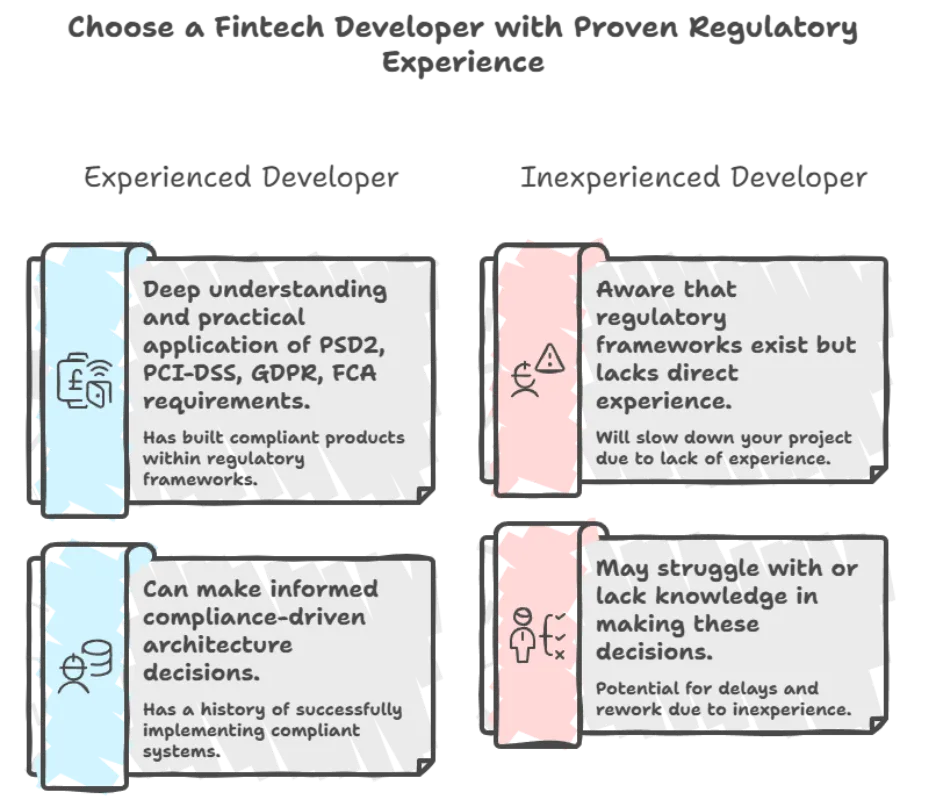
UK GDPR, FCA Consumer Duty, PCI DSS v4.0.1, Open Banking standards and AML/KYC requirements should all be familiar. Rather than asking whether they know these rules, ask how the rules shaped their past projects. The answer will show their real experience.
Step 5: Assess Their Technology Stack for Scalability
The best fintech development companies in the UK focus on sustainable technology, not just modern tools. Look for backend experience in Java, Python and Node.js, mobile work in Swift and Kotlin, cloud experience on AWS, Azure and Google Cloud, and AI for fraud detection and real-time decisions.
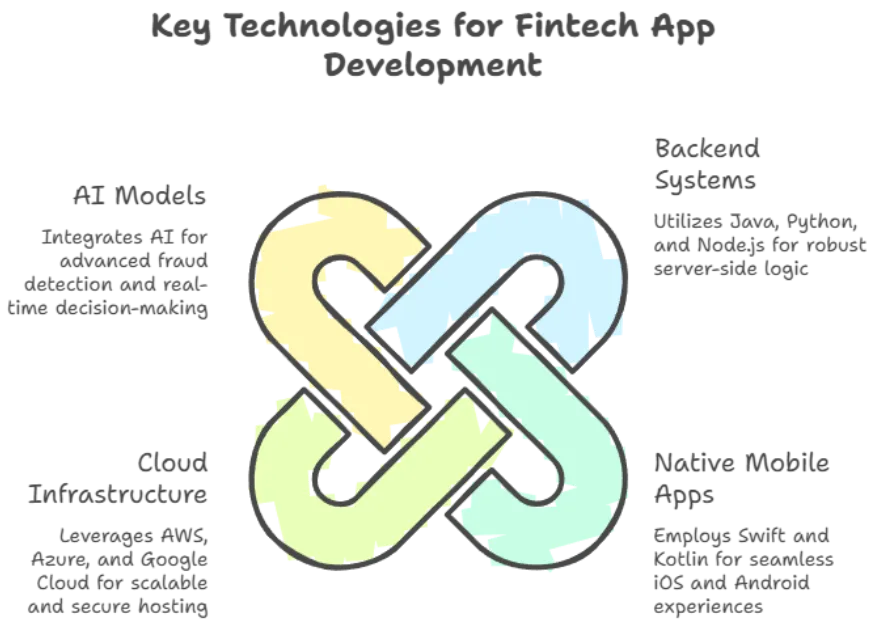
Tools only matter if the team designs the system well. A production-ready fintech app needs solid transaction logic, security, payment integrations, compliance systems and back-office tools. A team that treats fintech like a frontend project can fail under scale and fail compliance checks. Ask these questions first.
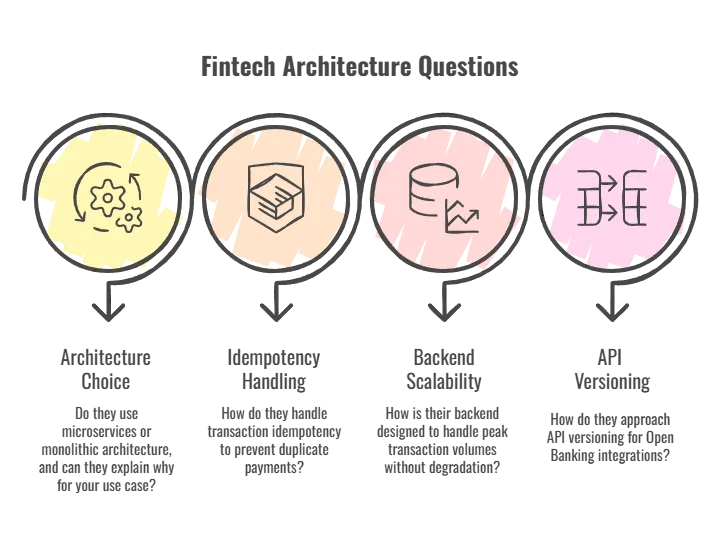
Step 6: Understand Engagement Models and Pricing Structure
Fintech app development costs in the UK depend mostly on how you engage the team and how complex the product is. There are three common models.
A fixed price model suits a clearly defined MVP or small project. You get budget certainty but little flexibility if requirements change mid-project.
A time and materials (T&M) model suits complex projects whose requirements evolve with regulation. It is flexible, but you need to watch costs closely.
A dedicated team model suits long-running products that need a stable team embedded in your process. Through staff augmentation you pay a predictable monthly rate and keep control of priorities, which works well for regulated products that never really stop changing.

Free cost estimator
What will your project cost?
Pick your features and get a price range and timeline in under two minutes. No email needed.
Estimate my costStep 7: Test Communication and Project Management Before You Sign
In fintech, clear communication is risk control. Regulations change, APIs fail and security issues appear mid-build. How fast they get fixed depends on how your partner communicates when something goes wrong.
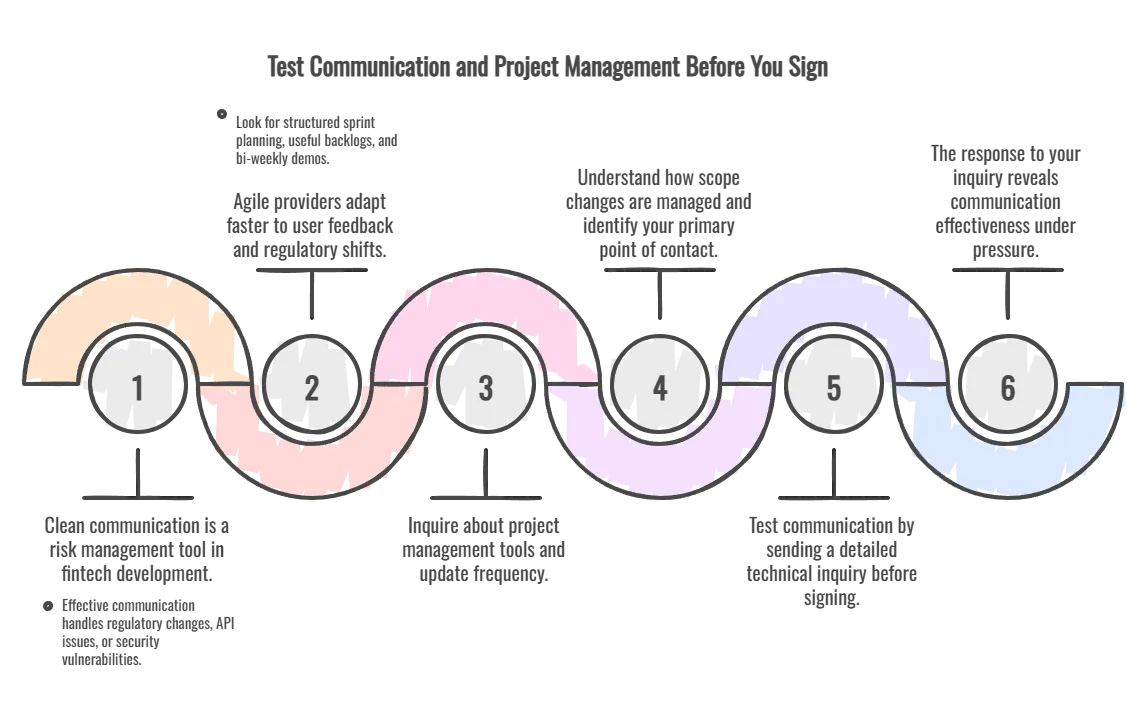
Pick teams that follow structured Agile practices: sprint planning, clear backlogs and regular demos, so you always know where the product stands. Ask which tools they use, how often they share updates and how they handle scope changes.
Step 8: Evaluate Post-Launch Support as Seriously as Development Capability
Launch is just the beginning. Security updates, compliance changes, performance monitoring and new features continue for the life of the app. Financial apps run 24/7, and without proper support your reputation is on the line.
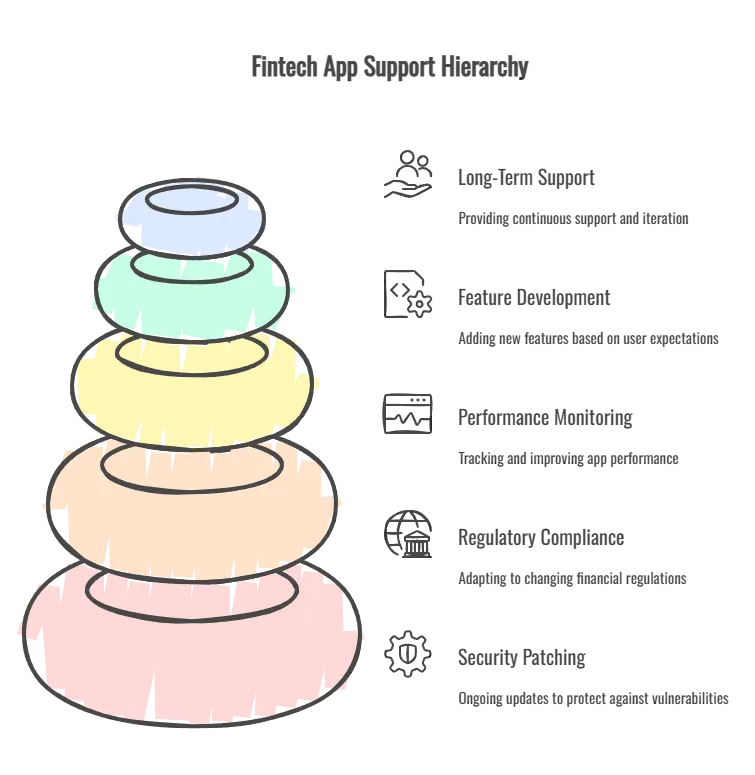
Make sure your partner offers a clear support agreement covering response times and ongoing monitoring. Ask how fast they respond to security issues and regulatory updates.
Free download
Take the vendor checklist with you
The questions to ask, a scoring sheet and the contract points to check. Free PDF.
Download my free checklistFrequently Asked Questions
1. Can a non-UK fintech development company build an FCA-compliant app?
Yes, if it has documented experience with FCA regulations, UK GDPR and Open Banking standards.
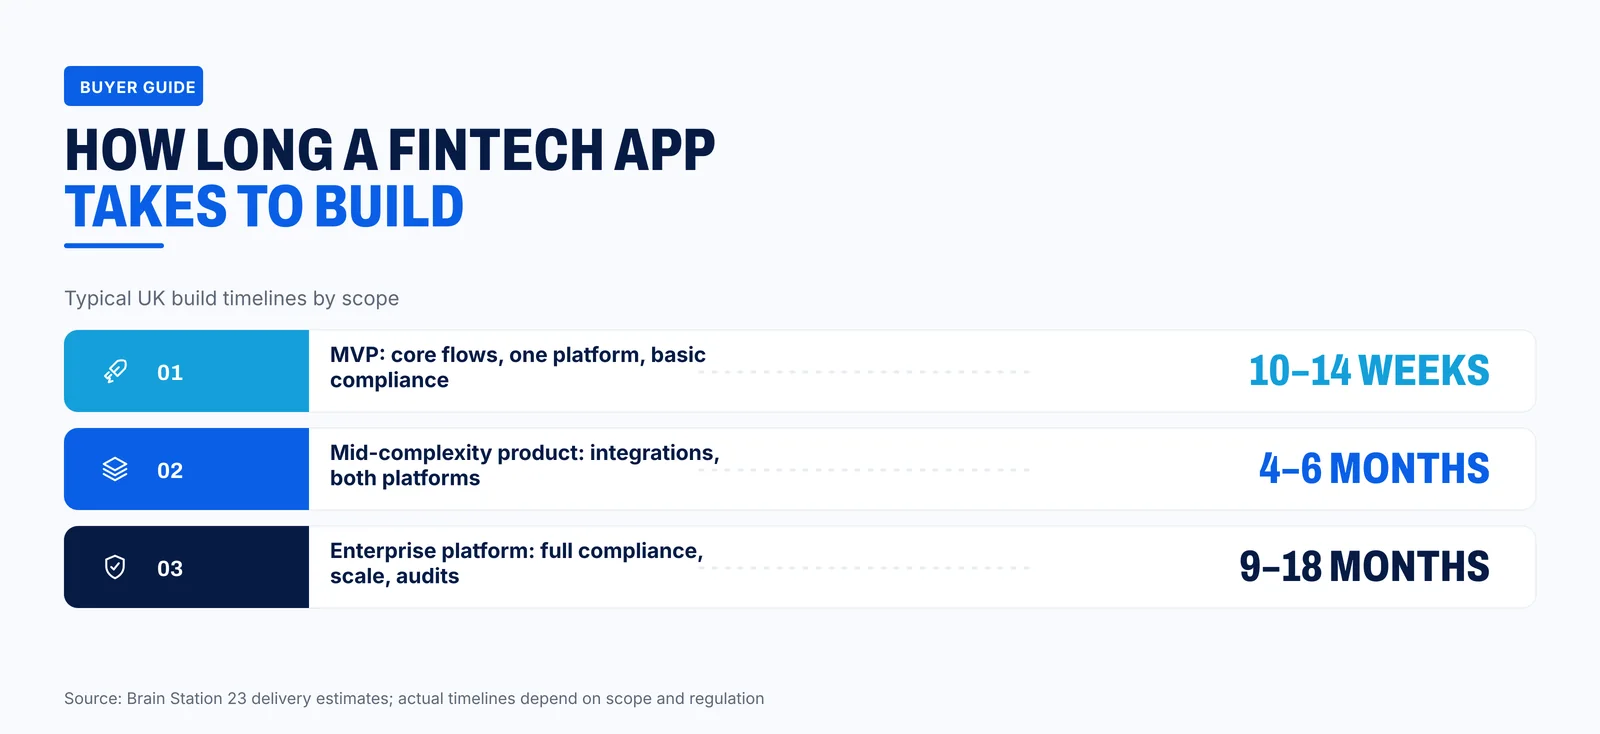
2. How long does it typically take to build a fintech app in the UK?
An MVP usually takes 10 to 14 weeks, a mid-complexity product 4 to 6 months, and an enterprise-grade platform 9 to 18 months depending on complexity.
3. Do I need my own FCA licence before I approach a development company?
No. A development team can start work before you are authorised. Getting FCA approval is your responsibility, not the developer’s.
4. What is the difference between a fintech app and a regular mobile app from a development perspective?
Fintech apps need built-in compliance, real-time transaction handling, strong data security and regulatory alignment. Standard apps rarely need all four.
5. Can I switch fintech development companies mid-project if things go wrong?
Yes, but it is expensive and disruptive. Clear contracts, IP ownership terms and proper documentation from day one avoid most of the pain.
6. Should I build natively or cross-platform for a fintech app?
Native is usually the safer choice for security and performance. For an MVP or internal tools where speed matters most, cross-platform often works better.
7. How do fintech development companies handle IP ownership?
Reputable firms transfer full IP ownership to you once payment is made. Make sure this is written into the contract.
Final Words
The UK fintech market does not reward hesitation. You face high consumer expectations, tight regulation and a gap between businesses and financial apps that widens every quarter. The right development partner handles the complex, compliance-heavy build for you.
Every company on this list among the top fintech app development companies in UK can do that. Only a few push customer satisfaction, scaling and post-launch support to the highest level.
This is where Brain Station 23 stands out: 12M+ engineering hours, a 4.9 Clutch rating from 21 verified reviews, and delivery across the full fintech product lifecycle.
The best time to start was yesterday. The second best time is now. Get in touch with Brain Station 23 and take the first step toward a fintech product your customers will trust.
Brain Station 23
Your next step
Ready to pick the right partner?
Tell us what you are building. In 30 minutes you will know the next step, the rough cost and who should build it, even if it is not us.
Book my free 30-minute call- 20+ years
- 900+ engineers
- 36+ countries
- CMMI Level 3
- ISO 27001
- SOC 2 Type II
Sources of Information
- Mordor Intelligence, United Kingdom Fintech Market: https://www.mordorintelligence.com/industry-reports/united-kingdom-fintech-market
- Open Banking Limited, Open banking in 2025: https://www.openbanking.org.uk/insights/open-banking-in-2025-now-part-of-the-uks-everyday-financial-life/
- Finder, Digital banking statistics 2026: https://www.finder.com/uk/digital-bank-statistics
- Pay.UK, Quarterly Statistical Report Q4 2025: https://www.wearepay.uk/wp-content/uploads/2026/03/Quarterly-Statistical-Report-2025-Q4.pdf
- Financial Conduct Authority, AI Live Testing service: https://www.fca.org.uk/news/press-releases/fca-set-launch-live-ai-testing-service
- IMARC Group, AI in Fintech Market: https://www.imarcgroup.com/ai-in-fintech-market
- FXC Intelligence, Cross-border payments market size: https://www.fxcintel.com/research/press-releases/new-data-cross-border-payments-market-now-worth-over-194tn-and-is-forecast-to-reach-320tn-by-2032
- UK Legislation, Data Protection Act 2018, section 157: https://www.legislation.gov.uk/ukpga/2018/12/section/157
- IBM, Cost of a Data Breach Report 2025: https://www.ibm.com/reports/data-breach
- Financial Conduct Authority, Starling Bank fine: https://www.fca.org.uk/news/press-releases/fca-fines-starling-bank-failings-financial-crime-systems-and-controls
- Cifas, Fraudscape 2026: https://www.cifas.org.uk/newsroom/fraudscape2026
- Experian, AI-driven fraud report 2025: https://www.experianplc.com/newsroom/press-releases/2025/new-report-from-experian-reveals-surge-in-ai-driven-fraud-
- Clutch, Brain Station 23 profile: https://clutch.co/profile/brain-station-23
Get the UK Fintech App Vendor Evaluation Checklist
Enter your email and we will send you the PDF.