

Imagine you open a bank account from your couch. No branch. No queue. No paper forms. Ten minutes, done.
That feels normal in Singapore now. Digital payments adoption in Singapore hit 92% in 2025. People already live on their phones. So, a bank that feels slow, or asks you to visit a branch, loses.
But someone has to build the app behind it. That someone is one of the top digital banking solution companies in Singapore working quietly in the background.
So, who are they? Which ones are worth your time?
Here’s a list of top 20 digital banking solution companies in Singapore for anyone looking for a build partner. We looked at what each company actually does, who they are best for, and where they are strong.
List of Top 20 Digital Banking Solution Companies in Singapore
| Sl. | Company | Founded | Experience | Team Size | Solution Type | Banking Focus Area | Core Services | Technology Expertise | Strengths & Certifications | Industries Served | Best For |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | Brain Station 23 | 2006 | 19+ years | 900+ | Services (custom build) | Digital banking platforms; Mobile wallets; Digital lending; e-KYC; Remittance | Internet and mobile banking platforms; Mobile wallet builds with P2P transfers, merchant payments and QR; Remittance platforms with multi-currency wallets and real-time FX; Digital lending with automated credit scoring and AI fraud protection; e-KYC and digital onboarding; Custom web and mobile app development; Staff augmentation; Managed services; Legacy modernisation; Cloud and DevOps; QA and test automation; AI/ML; Data engineering and BI | Java; Spring MVC; .NET; C#; Node.js; React; Angular; Vue.js; Python; Laravel; PHP; Flutter; iOS (Swift); Android (Kotlin); Golang; AWS; Azure; AI/ML; Blockchain; Adobe Experience Manager | CMMI Level 3; ISO 27001; ISO 9001; AWS, Microsoft, Adobe and Odoo partner; 1,000+ projects delivered since 2006 | Banking and NBFI; Fintech; Telecom; Pharma; Retail; e-Commerce; Education; Manufacturing; Startups | Banks, NBFIs and fintechs that want a custom-built digital banking platform and long-run engineering capacity at offshore cost |
| 2 | Zuhlke Engineering | 1968 | 55+ years | 1,900+ globally; 150 in Singapore | Services (end-to-end engineering) | Greenfield digital bank builds; Cloud-native architecture; App engineering | End-to-end digital bank delivery; Technical architecture and advisory; Cloud-native engineering; Mobile and web app development; Data and AI; 24/7 post-release operations | Java; Kotlin; Swift; .NET; AWS; Azure; Google Cloud; Kubernetes; test-driven development; AI/ML | Swiss engineering firm founded 1968; 17 locations across Europe and Asia; Apple Consultants Network member | Banking; Insurance; Healthcare; Public sector; Industrial | Launching a greenfield digital bank end to end, from architecture through live operations |
| 3 | Moneythor | 2013 | 12+ years | 32 | Product platform (engagement layer) | Personalisation; Personal financial management; Loyalty and gamification | Data-driven personalisation engine; Personal financial management; Insights and nudges; Budgets and savings goals; Predictive forecasts; Loyalty and referral programmes; Gamification; Campaign analytics | Java EE; REST APIs; machine learning; behavioural science models; on-premise or cloud deployment | Backed by Navis Capital Partners; led by CEO Martin Frick, formerly of Temenos; sits on top of any existing core banking system | Retail banking; SME and commercial banking; Digital banks; Fintechs | Banks that already have an app and need engagement, personalisation and PFM layered on top |
| 4 | Adnovum | 1988 | 35+ years | 700+ globally; 40+ in Singapore | Services (secure engineering) | Identity and access management; Secure banking apps; Digital onboarding | Custom banking application development; Systems integration; Identity and access management; Security engineering; Digital onboarding; Cloud enablement; Compliance | Java; Spring; Angular; .NET; Kubernetes; identity and access management; DevSecOps; Cloud | Swiss software engineering firm founded 1988; deep specialisation in identity, access management and security consulting | Banking; Insurance; Public sector | Security-critical and compliance-heavy banking software where identity is central |
| 5 | PALO IT | 2012 | 13+ years in Singapore | 700+ across 16 offices | Services (agile product engineering) | Banking and fintech products; Regtech; Insurtech | Agile software development; Digital product design; Cloud; Data and AI; DevOps; User research; Web and mobile app development | Java; Node.js; React; Python; AWS; Azure; Google Cloud; DevOps; AI; Blockchain | B Corp certified in Singapore, Hong Kong, Mexico and Thailand; World Economic Forum New Champion since 2021 | Banking and finance; Insurance; Energy and utilities; Government; Healthcare; Retail; Transport | Design-led agile product builds where sustainability and B Corp credentials matter to the client |
| 6 | Aleph Labs | 2006 | 19+ years | 300 | Services (design-led engineering) | Customer-facing banking apps; Digital product design | Digital product engineering; Financial, internet, mobile and desktop solutions; Mobile and web app development; UX/UI and total experience design; Cloud; Data | Swift; Kotlin; React; Node.js; Java; Cloud; design systems | Grown from a garage operation to roughly 300 staff; design and engineering under one roof; regional presence across Southeast Asia | Banking and financial services; Telecom; Retail; Government | Customer-facing banking apps where design quality carries as much weight as engineering |
| 7 | SmartOSC | 2006 | 19+ years | 1,000+ across 11 offices in 9 countries | Services (platform implementation) | Engagement banking rollout; Core integration; Digital onboarding | Digital banking implementation; Core banking integration; Digital onboarding; Web and mobile app development; UX/UI; Cloud; Managed services; QA | Java; .NET; Node.js; React; React Native; Flutter; AWS; Azure; Backbase; Adobe Commerce | Backbase implementation partner; Adobe Commerce APAC partner; recognised in Forrester Now Tech APAC Digital Experience Services | Banking and financial services; Retail and e-Commerce; Insurance; Government | Implementing a licensed engagement-banking platform rather than building a core from scratch |
| 8 | Luxoft (a DXC company) | 2000 | 25+ years | 17,000+ globally; 429 in Singapore | Services (specialist engineering) | Trading and risk platforms; Wealth technology; Digital channels | Banking and capital markets engineering; Trading and risk platforms; Wealth management technology; Digital channels; Cloud; Data engineering | Java; C++; Python; .NET; Murex; Calypso; Cloud; AI/ML; low-latency systems | Part of DXC Technology, a Fortune 500 IT services company; deep vendor-platform specialisation in Murex and Calypso; Finastra Capital Markets Partner of the Year | Banking; Capital markets; Wealth management; Automotive; Telecom | Trading, risk and wealth platforms where capital-markets depth matters more than app design |
| 9 | Virtusa | 1996 | 28+ years | 10,001+ (LinkedIn band) | Services (systems integration) | Open banking and APIs; Core modernisation; Digital channels | Banking application development; Core modernisation; Digital channels; API and open banking; Cloud migration; Data and analytics; QA engineering | Java; .NET; Pega; AWS; Azure; Google Cloud; APIs; AI/ML; open banking standards | Owned by EQT and CPP Investments; Pega Centre of Excellence in Singapore; regulator-facing open banking credentials | Banking and financial services; Insurance; Healthcare; Telecom | API and open-banking programmes with a regulator-facing dimension |
| 10 | Maveric Systems | 2000 | 25+ years | 2750 | Services (banking-only specialist) | Core banking transformation; Temenos services; Quality engineering | Core banking implementation and modernisation; Digital banking channels; Data engineering; Temenos implementation services; Quality engineering and assurance; Regulatory and compliance systems | Temenos; Java; Python; Kotlin; Swift; Informatica; Talend; Microsoft Azure; Kubernetes; AI/ML | 25+ years focused on a single vertical, banking; named a Major Contender in Everest Group’s Banking IT Services and Payments IT Services PEAK Matrix 2025; ranked #440 on the FT Asia-Pacific High-Growth Companies 2025 list | Retail banking; Corporate banking; Wealth management | Banks running a core banking or Temenos programme who want a partner that does nothing else |
| 11 | NashTech | 2000 | 25+ years | 2,300 engineers across 15 countries | Services (custom build) | Custom banking applications; Cloud and DevOps; QA automation | Custom software development; Digital banking applications; Cloud and DevOps; Data and AI; QA and test automation; Business process outsourcing; Managed services | Java; .NET; Node.js; React; Angular; Python; AWS; Azure; Google Cloud; Kubernetes; AI/ML | Part of the Nash Squared group; acquired by PAG; Google Cloud Premier Partner; named a Top 10 ICT company in Vietnam | Financial services; Retail; Education; Public sector; Technology | Cost-conscious custom builds delivered with UK-standard governance |
| 12 | Xebia | 2001 | 24+ years | 5,500+ | Services (composable engineering) | Composable digital bank stacks; Cloud and DevOps; Data and AI | Digital bank platform engineering; Core integration; Cloud and DevOps; Data and AI; Agile transformation; Software engineering; Low-code; Technical training | Java; Kotlin; Node.js; React; Kubernetes; AWS; Azure; Google Cloud; AI/ML; DevOps toolchain | 16 countries and 28 offices; Xebia Academy training arm; strong DevOps, cloud and agile engineering reputation | Banking and fintech; Retail; Travel; Automotive; Telecom | Cloud-native, composable digital bank stacks assembled from best-of-breed components |
| 13 | Endava | 2000 | 25+ years | 11,600 globally | Services (product engineering) | Payments engineering; Core modernisation; Digital acceleration | Payments and banking software delivery; Core modernisation; Digital acceleration; Product engineering; Cloud; Data and AI; QA automation | Java; .NET; Node.js; React; Python; AWS; Azure; Google Cloud; Kubernetes; AI/ML | NYSE listed (DAVA); 69 offices across 29 countries; 619 active clients; deep payments engineering heritage | Payments; Banking and capital markets; Insurance; Telecom; Retail | Payments-adjacent engineering and modernisation with nearshore-style delivery in Asia |
| 14 | FPT Software | 1999 | 25+ years | 33,000+ across 30+ countries | Services (offshore delivery at scale) | Core banking implementation; Digital channels; Legacy modernisation | Banking application development; Core banking implementation; Digital channels; Legacy modernisation; Cloud; Data and AI; RPA and hyperautomation; QA | Java; .NET; Node.js; React; iOS; Android; AWS; Azure; Google Cloud; AI/GenAI; RPA (akaBot); ServiceNow; SAP | Largest IT services group in ASEAN; USD 1.34B revenue in 2025; 1,100+ clients including 130+ Fortune Global 500 companies | Banking and financial services; Insurance; Healthcare; Manufacturing; Automotive; Aviation | Large-volume banking delivery where offshore cost efficiency is the deciding factor |
| 15 | Temenos | 1993 | 30+ years | 5000 | Product platform | Core banking; Digital front-end; Payments; Wealth | Core banking platform (Transact); Digital banking front-end (Infinity); Payments; Wealth management; Financial crime mitigation; SaaS banking | Java; cloud-native microservices; APIs; AWS; Azure; Google Cloud; AI for banking | Listed on the SIX Swiss Exchange (TEMN); one of the most widely deployed core banking products globally; first core banking software certified on Huawei Public Cloud for Asia | Retail banking; Corporate banking; Wealth management; Islamic banking; Fintechs | Banks replacing or modernising a core banking system on a proven global platform |
| 16 | CREALOGIX | 1996 | 25+ years | 380+ across 12 offices in 7 countries | Product platform | Digital front-end; Digital wealth management; Open banking orchestration | Digital banking front-end (Digital Hub); Mobile and online banking; Digital wealth management; Onboarding; Open banking orchestration; Banking-as-a-Service | Cloud and SaaS; APIs; open banking; Angular; Java; microservices | Swiss FinTech 100 company; acquired by Vencora; previously listed on the SIX Swiss Exchange | Retail banking; Private banking; Wealth management; Public sector | Wealth and private banks that want a polished digital front-end without replacing the core |
| 17 | Contemi Solutions | 2001 | 24+ years | 140 | Hybrid (software plus services) | Wealth management platform; Banking and cash management; Capital markets | Wealth Intelligence (WIN) front-to-back wealth platform; Banking and cash management software; Client onboarding; Portfolio management; Trading and order management; Custody and corporate actions; Implementation and support services | Cloud-based modular architecture; APIs; front-to-back platform integration | Acquired by Profile Software in December 2025; won a hat-trick of WealthTech Asia Awards in 2021 | Wealth and asset management; Private banking; Capital markets; Insurance | Wealth managers and private banks needing a front-to-back platform with regional implementation support |
| 18 | Geniusto | 2018 | 7+ years | 64 | Product platform plus implementation | Core banking; Digital onboarding; Payments orchestration; Omni-channel | GO Core Banking (cloud ledgering); GO Onboarding (KYC/KYB, biometrics, risk scoring); GO Payment (low-code payment orchestration); GO Omni-channel (web and mobile banking); Implementation and deployment; IT consulting | Open architecture; low-code; microservices; APIs; cloud-based ledgering | ISO 9001 and ISO 27001 certified; digital bank launchable in weeks on low-code, open architecture | Banks; Credit unions; Payment providers; Remittance companies; e-money issuers | Smaller banks and e-money institutions wanting a bank-in-a-box launched in weeks |
| 19 | Bank-Genie | 2016 | 9+ years | 40 to 50 | Product platform | Modular core banking; Branchless and agent banking; Digital onboarding | BanqIn modular core banking; Digital onboarding; Video banking; Agent and branchless banking; Digital lobby and queue management; Cheque digitisation; Contactless payments; Remote implementation | Cloud-native architecture; web; mobile; tablet; kiosk; APIs | Backed by FMO, the Dutch Development Bank, and SBI Ven Capital; enables a bank to open a virtual branch at very low cost | Commercial banks; Neo banks; Micro-finance institutions; Credit unions; Fintechs | Micro-finance institutions and banks extending services into low-connectivity or remote markets |
| 20 | Buuuk | 2008 | 17+ years | Under 50 | Services (design-led app studio) | Consumer banking and payments apps; Remittance apps | Mobile app development (iOS and Android); Digital strategy; UI/UX design; Custom software; Server-side development; Platform integration | Swift; Kotlin; Ruby; Golang; React; iBeacon; Bluetooth and GPS location services | Delivered 100+ apps since 2008; team includes one of only two Apple Design Award winners in Southeast Asia | Banking and payments; Telecom; Automotive; Retail; Government | Consumer-facing banking and remittance apps where design and app-store polish decide adoption |
Top 20 Digital Banking Solution Companies in Singapore
Now the real part. Here is who they are, and why they made the list. We looked beyond the shiny marketing. What each one really does. Who they fit. Where they shine, and where they fall short. Pick and talk to the ones that match your plan.

1. Brain Station 23
Let’s Start with the one that can build the whole thing from scratch.
Brain Station 23 is a software and fintech company that has been shipping code since 2006. Nearly two decades of it. And it does not sell you a boxed product. It builds the digital banking platform you actually want, matches your rules, your market, and your regulator.
That matters more than it sounds. A lot of vendors hand you a template and ask you to bend around it. Brain Station 23 does the opposite. Internet and mobile banking, mobile wallets with P2P and QR, remittance with real-time FX, digital lending with automated credit scoring, and digital onboarding with e-KYC. All custom. All yours.
And here is the quiet advantage. You get a real engineering team, long term, at offshore cost. Not a quick project and goodbye. A partner that stays, modernizes the old stuff, runs the cloud, and keeps the lights on. If you want a bank-grade build without paying unexpected rates, this is the name to call.
One more thing worth knowing. The team works Singapore hours from Kuala Lumpur, so your daily standups actually happen at a sane time. No 3 a.m. calls. That alone saves a lot of pain on a long build.
Founded: 2006
Headquarters: Dhaka, Bangladesh, with a regional office in Kuala Lumpur serving Singapore including 6 total global offices
Experience: 19+ years
Team size: 850+
Strengths: CMMI Level 3, ISO 27001, ISO 9001, partner to AWSMicrosoftAdobe and Odoo, 1,000+ projects delivered in 36+ countries
Industries: Banking and NBFIFintechTelecomPharmaRetaile-CommerceEducationManufacturingStartups
Best for: Banks, NBFIs and fintechs that want a custom platform and a team that sticks around
- Internet and mobile banking
- mobile wallets
- remittance
- digital lending
- e-KYC onboarding
- custom web and mobile apps
- staff augmentation
- cloud and DevOps
- QA automation
- AI/ML
- data engineering
- Java
- Spring
- .NET
- Node.js
- React
- Angular
- Vue
- Python
- Laravel
- Flutter
- Swift
- Kotlin
- Golang
- AWS
- Azure
- Blockchain

2. Zuhlke Engineering
Zuhlke has been building software since 1968, and it does something few can pull off. It takes a digital bank from a blank page to a live product. Architecture, engineering, launch, and then round-the-clock support after go-live. The full journey.
If you are starting a bank with nothing but a license and a plan, this is the kind of partner that keeps the wheels on.
Fair warning though. Swiss engineering does not come cheap. You pay for the pedigree, and for some builds that price is well worth it. For others, it stings.
Founded: 1968
Headquarters: Switzerland, with roughly 150 staff in Singapore
Team size: 1,900+ globally
Strengths: 17 locations across Europe and AsiaApple Consultants Network member
Industries: BankingInsuranceHealthcarePublic sectorIndustrial
Best for: Launching a greenfield digital bank from architecture through live operations
- End-to-end digital bank delivery
- technical architecture
- cloud-native engineering
- mobile and web apps
- data and AI, 24/7 operations
- Java
- Kotlin
- Swift
- .NET
- AWS
- Azure
- Google Cloud
- Kubernetes
- AI/ML

3. Moneythor
Already have an app? Good. This one makes it smarter.
Moneythor does not rebuild your bank. It runs on top of whatever core you have and adds the clever bits. Personal financial management. Nudges. Savings goals. Little touches that make customers feel the app knows them.
Think of it as the engagement layer. The part that turns a boring balance screen into something people open every day. It will not build your core, and it does not pretend to. Bring your own bank. Moneythor makes it sing.
Founded: 2013
Headquarters: Singapore
Team size: 32
Strengths: Backed by Navis Capital Partnersled by a CEO formerly of Temenosworks on top of any core banking system
Industries: Retail bankingSME and commercial bankingDigital banksFintechs
Best for: Banks that already have an app and want personalization and PFM layered on
- Data-driven personalization
- personal financial management
- insights and nudges
- budgets and goals
- loyalty and referral programmes
- gamification
- campaign analytics
- Java EE
- REST APIs
- machine learning
- behavioural science models
- cloud or on-premise

4. Adnovum Singapore Pte. Ltd.
Some banks lose sleep over one thing. Security. Adnovum is built for exactly that. This Swiss firm has spent decades on identity, access, and locking down the stuff that cannot leak. When your banking software has to pass hard compliance checks, and identity is the whole game, this is a safe pair of hands.
Just know what you are hiring them for. This is not the crew for a playful consumer app. Their gift is the locked vault, not the pretty front door.
Founded: 1988
Headquarters: Switzerland, with 40+ staff in Singapore
Team size: 700+ globally
Strengths: Deep specialisation in identityaccess management and security consulting
Industries: BankingInsurancePublic sector
Best for: Security-critical, compliance-heavy banking software where identity is central
- Custom banking apps
- systems integration
- identity and access management
- security engineering
- digital onboarding
- cloud enablement
- compliance
- Java
- Spring
- Angular
- .NET
- Kubernetes
- DevSecOps
- Cloud

5. Palo IT
PALO IT builds banking and fintech products the modern way. Short sprints. Real user research. Design that people actually enjoy using. And it wears its B Corp badge with pride. So if sustainability matters to your board, that lands well here.
Want a build partner that moves quick and thinks about impact? This one fits. Mid-size product builds are the sweet spot. A giant core replacement is not really their lane, and they will tell you so.
Founded: 2012 in Singapore
Headquarters: Global, 16 offices
Team size: 700+
Strengths: B Corp certified in SingaporeHong KongMexico and ThailandWorld Economic Forum New Champion since 2021
Industries: Banking and financeInsuranceEnergyGovernmentHealthcareRetailTransport
Best for: Design-led agile builds where sustainability credentials matter
- Agile software development
- digital product design
- cloud
- data and AI
- DevOps
- user research
- web and mobile apps
- Java
- Node.js
- React
- Python
- AWS
- Azure
- Google Cloud
- DevOps
- AI
- Blockchain

6. Aleph Labs
This one grew from a garage. Now it runs banking apps across Southeast Asia.
Aleph Labs cares about how the app feels. Design and engineering under one roof, so the thing looks good and works well at the same time. For a customer-facing mobile banking app where a clunky screen loses users, that combination pulls its weight.
Design people, who can also ship. Nice mix. And the regional roots help more than you would guess. They build for how Southeast Asians actually bank. Not just for a Western design trend copied from abroad.
Founded: 2006
Headquarters: Singapore, with regional presence across Southeast Asia
Team size: 300
Strengths: Design and engineering in one housestrong regional footprint
Industries: Banking and financial servicesTelecomRetailGovernment
Best for: Customer-facing banking apps where design quality matters as much as engineering
- Digital product engineering
- financial and mobile solutions
- web and mobile apps
- UX/UI and total experience design
- cloud
- data
- Swift
- Kotlin
- React
- Node.js
- Java
- Cloud
- design systems
7. SmartOSC
Do not want to build a core from zero? Smart move. This is your implementer. SmartOSC takes licensed platforms, like Backbase, and rolls them out for you. Core integration, digital onboarding, the works.
You just buy the engine, let SmartOSC fit it into your car. Just be clear on the brief. If you want a core built from scratch, look elsewhere. Their real strength is taking a bought platform and getting it live, fast.
Founded: 2006
Headquarters: Singapore and regional
Team size: 1,000+ across 11 offices in 9 countries
Strengths: Backbase implementation partnerAdobe Commerce APAC partnernamed in Forrester Now Tech APAC
Industries: Banking and financial servicesRetail and e-CommerceInsuranceGovernment
Best for: Implementing a licensed engagement-banking platform instead of building from scratch
- Digital banking implementation
- core banking integration
- digital onboarding
- web and mobile apps
- UX/UI
- cloud
- managed services
- QA
- Java
- .NET
- Node.js
- React
- React Native
- Flutter
- AWS
- Azure
- Backbase
- Adobe Commerce
8. Luxoft
Now we go deep into the money machine. Luxoft, part of Fortune 500 firm DXC, lives in the hard corners of finance. Trading platforms. Risk systems. Wealth tech. The low-latency, high-stakes stuff where a millisecond counts.
This is not app design. This is capital-markets muscle. Overkill for a simple retail app, honestly. But when the numbers get scary and the risk is real, few names carry this much weight.
Founded: 2000
Headquarters: Global, 429 staff in Singapore
Team size: 17,000+ globally
Strengths: Part of DXC Technologydeep Murex and Calypso specialisationFinastra Capital Markets Partner of the Year
Industries: BankingCapital marketsWealth managementAutomotiveTelecom
Best for: Trading, risk and wealth platforms where capital-markets depth beats app polish
- Banking and capital markets engineering
- trading and risk platforms
- wealth technology
- digital channels
- cloud
- data engineering
- Java
- C++
- Python
- .NET
- Murex
- Calypso
- Cloud
- AI/ML
- low-latency systems

9. Virtusa
Open banking is a headache. Virtusa likes headaches.
APIs. Core modernisation. Regulator-facing open banking programmes. Virtusa handles the messy integration work that connects old systems to new rails. It runs a Pega Centre of Excellence right here in Singapore, so process-heavy builds are home turf.
When the regulator is watching, you want a partner that has done this before. It moves at big-company pace, mind you. Great for regulated, heavyweight work. A little less nimble if you are a five-person startup in a hurry.
Founded: 1996
Headquarters: Global
Team size: 10,000+
Strengths: Owned by EQT and CPP InvestmentsPega Centre of Excellence in Singaporeregulator-facing open banking credentials
Industries: Banking and financial servicesInsuranceHealthcareTelecom
Best for: API and open-banking programmes with a regulator-facing side
- Banking app development
- core modernisation
- digital channels
- API and open banking
- cloud migration
- data and analytics
- QA
- Java
- .NET
- Pega
- AWS
- Azure
- Google Cloud
- APIs
- AI/ML
- open banking standards

10. Maveric Systems
Twenty-five years. One industry. Banking. Nothing else. That kind of focus is rare. Maveric does core banking transformation and Temenos work all day, every day. So when your core banking programme starts to wobble, you get a partner who has seen your exact problem a hundred times.
Specialists beat generalists on the hard stuff. Simple as that. Step outside core banking and Temenos, though, and they are less of a fit. Stay inside it, and very few names match them.
Founded: 2000
Headquarters: Global
Team size: 2,750
Strengths: 25+ years in banking onlyMajor Contender in Everest Group Banking IT Services PEAK Matrix 2025, ranked #440 on the FT Asia-Pacific High-Growth list 2025
Industries: Retail bankingCorporate bankingWealth management
Best for: Banks running a core banking or Temenos programme who want a pure specialist
- Core banking implementation and modernisation
- digital channels
- data engineering
- Temenos implementation
- quality engineering
- regulatory systems
- Temenos
- Java
- Python
- Kotlin
- Swift
- Informatica
- Talend
- Azure
- Kubernetes
- AI/ML

11. NashTech
NashTech gives you custom builds run to UK-standard process, but delivered from lower-cost engineering hubs. Part of the Nash Squared group. A Google Cloud Premier Partner too. So you get discipline and value at once, which is a rare pairing.
Good governance, gentle price tag. For a cost-conscious build that still ticks the compliance boxes, take a look. The governance-heavy way of working means less cowboy energy on your project. Some teams love that steadiness. Others find it a touch slow. Know which one you are.
Founded: 2000
Headquarters: UK and Vietnam
Team size: 2,300 engineers across 15 countries
Strengths: Part of Nash Squaredacquired by PAGGoogle Cloud Premier PartnerTop 10 ICT company in Vietnam
Industries: Financial servicesRetailEducationPublic sectorTechnology
Best for: Cost-conscious custom builds with UK-standard governance
- Custom software
- digital banking apps
- cloud and DevOps
- data and AI
- QA automation
- BPO
- managed services
- Java
- .NET
- Node.js
- React
- Angular
- Python
- AWS
- Azure
- Google Cloud
- Kubernetes
- AI/ML

12. Xebia
Do not want one giant system? Build it from parts. Xebia is the composable crowd. It assembles a digital bank from best-of-breed pieces, all cloud-native, all snapped together the modern way. Strong on DevOps, cloud, and agile. It even runs its own training academy.
If your architecture team says “composable,” they mean this. One catch. You need people who know what they want. Hand Xebia a blank brief and the build drifts. Hand them a clear vision and they fly.
Founded: 2001
Headquarters: Global, 28 offices in 16 countries
Team size: 5,500+
Strengths: Xebia Academy training armstrong DevOpscloud and agile reputation
Industries: Banking and fintechRetailTravelAutomotiveTelecom
Best for: Cloud-native, composable bank stacks built from best-of-breed parts
- Digital bank platform engineering
- core integration
- cloud and DevOps
- data and AI
- agile transformation
- low-code
- technical training
- Java
- Kotlin
- Node.js
- React
- Kubernetes
- AWS
- Azure
- Google Cloud
- AI/ML
- DevOps toolchain

13. Endava
Endava is NYSE-listed and carries a deep payments heritage. It fixes creaky old cores, speeds up digital delivery, and does the payments plumbing that most people never see but everyone relies on. They have offices across 29 countries, with delivery you can reach from Asia.
When the payments engine matters most, this name comes up. Listed and large, so the pricing reflects that. But the payments depth usually earns it back. You are paying for a team that has broken and fixed these systems many times over.
Founded: 2000
Headquarters: Global, 69 offices in 29 countries
Team size: 11,600
Strengths: NYSE listed, 619 active clientsdeep payments engineering heritage
Industries: PaymentsBanking and capital marketsInsuranceTelecomRetail
Best for: Payments-adjacent engineering and modernisation with nearshore-style delivery in Asia
- Payments and banking software delivery
- core modernisation
- digital acceleration
- product engineering
- cloud
- data and AI
- QA automation
- Java
- .NET
- Node.js
- React
- Python
- AWS
- Azure
- Google Cloud
- Kubernetes
- AI/ML

14. FPT Software
Need scale? Real scale? Here it is.
FPT is the biggest IT services group in ASEAN, with 33,000+ people. When a project is huge, and cost efficiency decides the winner, FPT is hard to beat on price and volume. Core banking, digital channels, legacy modernisation, all delivered at scale.
Big job, tight budget. That is the FPT sweet spot. The flip side of scale is warmth. For a tiny bespoke project, a smaller shop may simply care more about your one app. Match the size of the partner to the size of the job.
Founded: 1999
Headquarters: Vietnam, 30+ countries
Team size: 33,000+
Strengths: Largest IT services group in ASEANUSD 1.34B revenue in 2025, 1,100+ clients including 130+ Fortune Global 500
Industries: Banking and financial servicesInsuranceHealthcareManufacturingAutomotiveAviation
Best for: Large-volume banking delivery where offshore cost efficiency decides
- Banking app development
- core banking implementation
- digital channels
- legacy modernisation
- cloud
- data and AI
- RPA
- QA
- Java
- .NET
- Node.js
- React
- iOS
- Android
- AWS
- Azure
- Google Cloud
- GenAI
- RPA (akaBot)
- ServiceNow
- SAP

15. Temenos
Temenos makes the core banking product that runs under a huge chunk of the world’s banks. Transact for the core, infinity for the front-end, plus payments and wealth. It is not a services shop. It is the platform itself. Proven, global, everywhere.
Replacing your core? This is the safe, obvious contender.
Remember what it is, though. A platform, not a builder. You still need an implementer to fit it to your bank. So budget for both the license and the team that installs it.
Founded: 1993
Headquarters: Switzerland
Team size: 5,000
Strengths: Listed on the SIX Swiss Exchangeone of the most widely deployed core banking products globally
Industries: Retail bankingCorporate bankingWealth managementIslamic bankingFintechs
Best for: Banks replacing or modernising a core banking system on a proven global platform
- Core banking platform (Transact)
- digital front-end (Infinity)
- payments
- wealth management
- financial crime mitigation
- SaaS banking
- Java
- cloud-native microservices
- APIs
- AWS
- Azure
- Google Cloud
- AI for banking

16. Crealogix
CREALOGIX gives private and wealth banks a polished digital front-end without ripping out the core underneath. Online and mobile banking, digital wealth tools, open banking orchestration, even Banking-as-a-Service. Swiss FinTech 100. Quietly excellent at the front-end layer.
Keep your core. Just make the face of it beautiful. A retail-first neobank might find it a bit wealth-heavy. Private and wealth banks, on the other hand, feel right at home the moment they open the box.
Founded: 1996
Headquarters: Switzerland, 12 offices in 7 countries
Team size: 380+
Strengths: Swiss FinTech 100 companyacquired by Vencora
Industries: Retail bankingPrivate bankingWealth managementPublic sector
Best for: Wealth and private banks wanting a strong digital front-end without replacing the core
- Digital banking front-end (Digital Hub)
- mobile and online banking
- digital wealth management
- onboarding
- open banking orchestration
- Banking-as-a-Service
- Cloud and SaaS
- APIs
- open banking
- Angular
- Java
- microservices
17. Contemi Solutions
If you are a wealth manager with a long to-do list, read on.
Contemi runs a front-to-back wealth platform called WIN. Onboarding, portfolios, trading, custody, all in one flow. And it pairs the software with regional implementation hands. So you are not left alone after go-live. Recently acquired by Profile Software, which adds more muscle.
One platform, the whole wealth journey, local support included. It is a smaller team, so play to that. Pick Contemi for wealth and private banking, not for a giant nationwide retail rollout. Right tool, right job.
Founded: 2001
Headquarters: Singapore and regional
Team size: 140
Strengths: Acquired by Profile Software in December 2025, won a hat-trick of WealthTech Asia Awards in 2021
Industries: Wealth and asset managementPrivate bankingCapital marketsInsurance
Best for: Wealth managers needing a front-to-back platform with regional implementation support
- Wealth Intelligence (WIN) platform
- banking and cash management software
- client onboarding
- portfolio management
- trading
- custody
- implementation and support
- Cloud-based modular architecture
- APIs
- front-to-back integration

18. Geniusto
Want a bank live in weeks, not years? Here is the shortcut. Geniusto is a bank-in-a-box. Core ledgering, onboarding with KYC and biometrics, payment orchestration, and omni-channel banking, all on low-code, open architecture. A newer name, founded in 2018, but built for speed. Smaller banks and e-money firms love that.
Less waiting. More launching. It is a young company, so the track record is shorter than the veterans above. But if a fast, lean launch is the goal, that speed often matters more than a long history.
Founded: 2018
Headquarters: Singapore
Team size: 64
Strengths: ISO 9001 and ISO 27001 certifieddigital bank launchable in weeks
Industries: BanksCredit unionsPayment providersRemittance companiese-money issuers
Best for: Smaller banks and e-money institutions wanting a bank-in-a-box in weeks
- GO Core Banking (cloud ledgering)
- GO Onboarding (KYC/KYB
- biometrics
- risk scoring)
- GO Payment (low-code orchestration)
- GO Omni-channel (web and mobile)
- implementation
- IT consulting
- Open architecture
- low-code
- microservices
- APIs
- cloud-based ledgering
19. Bank-Genie
Bank-Genie is built for reach. Branchless banking, agent banking, video banking, and a modular core that lets a bank open a virtual branch for very little money. Perfect for micro-finance and low-connectivity markets. Backed by FMO, the Dutch development bank, which tells you where its heart is.
Do not expect a slick, big-city neobank vibe here. That is not the mission. This is banking built to go where others will not, at a cost that makes remote markets work.
Founded: 2016
Headquarters: Singapore
Team size: 40 to 50
Strengths: Backed by FMO and SBI Ven Capitalopens a virtual branch at very low cost
Industries: Commercial banksNeo banksMicro-finance institutionsCredit unionsFintechs
Best for: Micro-finance institutions and banks reaching into remote or low-connectivity markets
- BanqIn modular core banking
- digital onboarding
- video banking
- agent and branchless banking
- digital lobby and queue management
- cheque digitisation
- contactless payments
- Cloud-native architecture
- web
- mobile
- tablet
- kiosk
- APIs

20. Buuuk
Buuuk is a design-led app studio that has shipped 100+ apps since 2008. Consumer banking, payments, remittance, all with real craft. Its team even includes one of only two Apple Design Award winners in Southeast Asia. When the app store rating decides whether people download you, that polish pays off.
A small studio cannot run a full core banking programme, and would never claim to. But for the app itself, the part your customer holds in their hand, very few match this level of finish.
Founded: 2008
Headquarters: Singapore
Team size: Under 50
Strengths: 100+ apps delivered since 2008, Apple Design Award winner on the team
Industries: Banking and paymentsTelecomAutomotiveRetailGovernment
Best for: Consumer banking and remittance apps where design decides adoption
- Mobile app development (iOS and Android)
- digital strategy
- UI/UX design
- custom software
- server-side development
- platform integration
- Swift
- Kotlin
- Ruby
- Golang
- React
- iBeacon
- Bluetooth and GPS
So What Does a Digital Banking Company Actually Do?
Fair question.
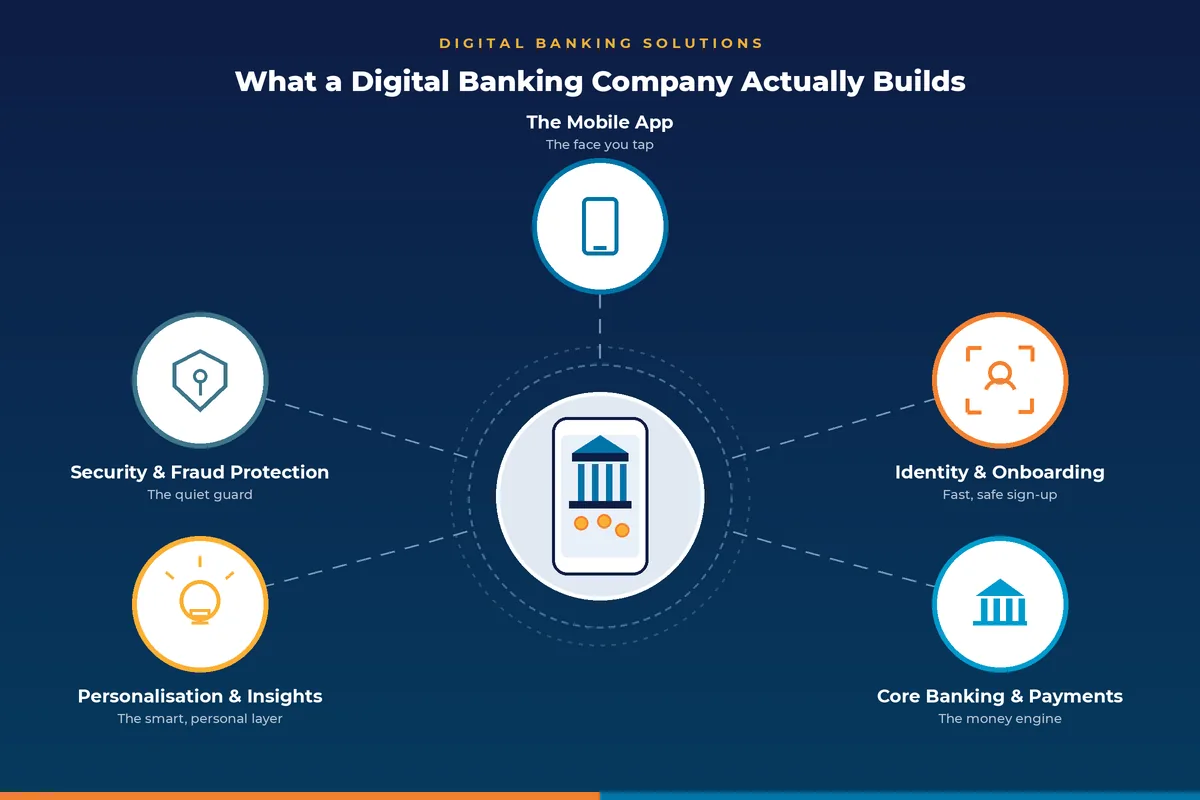
In plain words, they build the tech that lets a bank run on a phone. No branch is needed. But “the tech” is really a few different jobs stacked on top of each other. Here are the main ones.
The Mobile App
This is the part you actually touch. The screen, the buttons, the balance, the transfers. It lives in your pocket, and it is the face of the whole bank. Get it clunky and people delete it fast. Get it clean and open it every single day. First impressions count a lot here.
Identity and Onboarding
How you get in. A face scan, an ID check, a few taps, and your account is open. This is e-KYC and digital onboarding, and it has to feel fast and safe at the same time. Too slow or too fiddly, and people quit halfway. That drop-off is where banks quietly lose real customers.
Core Banking and Payments
The engine room. This is the part that moves cash. Transfers, payments, lending, and the ledger that tracks every single cent. Most of it is core banking, humming away where you never look. When it works, money just moves in seconds. You never think about it. And that is the whole point.
Personalization and Insights
The clever layer is on top. Nudges, budgets, savings goals, and small insights that feel personal to you. This is where an app stops being a plain calculator and starts feeling like a helper that gets you. Little touches, done well, build big loyalty over time. People stay for it.
Security and Fraud Protection
The quiet guard. Fraud checks, encryption, and identity locks, all running in the background where nobody claps for them. Boring on paper, yes. But this is the exact reason you trust an app with your whole salary. One breach and that trust is gone for good. So, it comes first.
What Is the Difference Between Digital Bank and Neobank?
People mix these up all the time. In plain terms, they are close cousins.
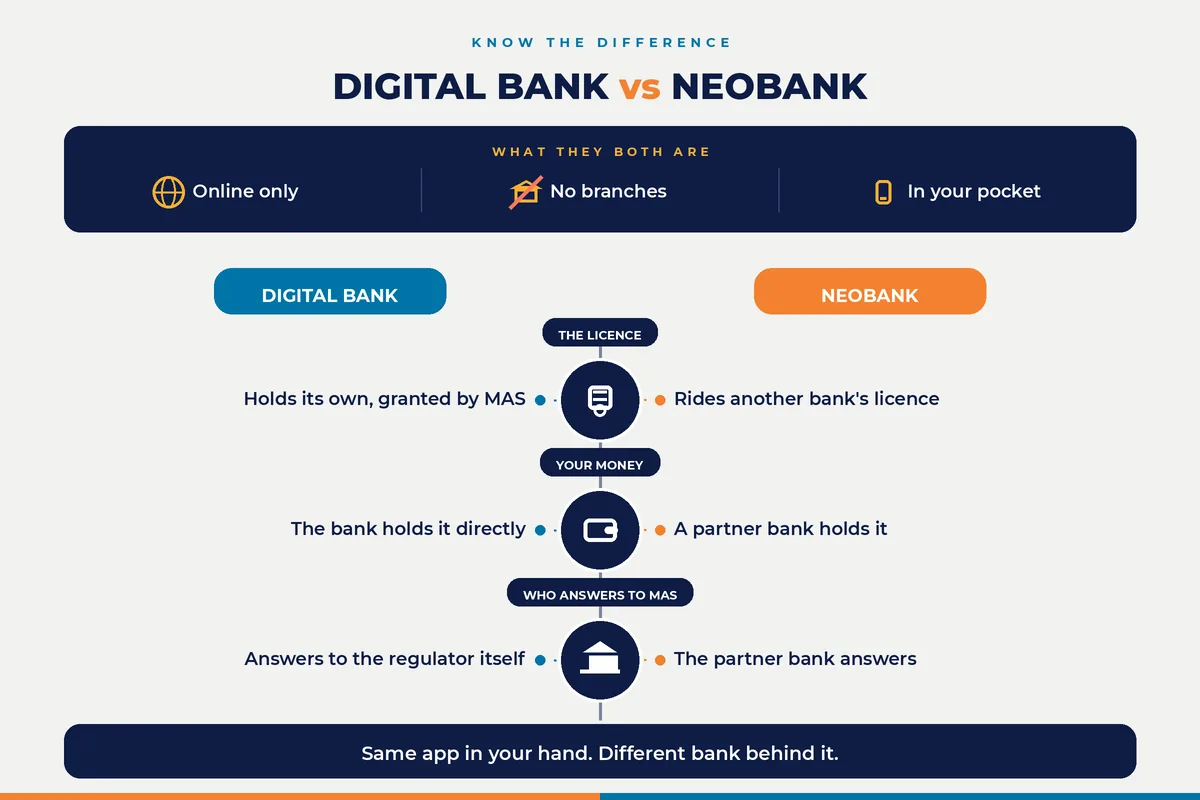
Both live online. Both skip the branches. Both run from an app in your pocket. So far, the same.
The gap is the license. A neobank usually rides another bank’s license, offering a slick app on top of someone else’s banking. A digital bank holds its own license, granted by the regulator, and stands on its own two feet.
For you as a user, the app often feels identical. The difference shows underneath, in who actually holds your money and answers to MAS. Worth knowing before you pick one.
Build Your Own, or Buy a Platform?
This is the big fork in the road. And people get it wrong all the time.

Two paths. Build it yourself with a partner, or buy a ready platform and roll it out. Both work. Both have a catch. The real trick is knowing which catch you can live with. So before you pick, look at them side by side.
So which is right? Depends on your hurry and your budget. In a rush with a standard product? Buy. Building something the market has not seen, or planning for the long haul? Build.
And here is the part people miss. You can mix the two. Buy the core, build your own front-end on top. Plenty of banks do exactly that, and get the best of both.
Digital Banking Compliance in Singapore You Should Know
You cannot talk banking in Singapore without talking about the regulator. It shapes everything.

Singapore is strict. On purpose. That is exactly why people trust their banks here in the first place. But those same rules land on you the moment you build. Every feature. Every data field. Every login.
Pick a partner who does not know the rules, and you learn them the hard way. Pick one who does, and half your compliance worry just melts away. So let us keep it simple. Here is what actually matters.
Who Regulates Digital Banking in Singapore?
One name. The Monetary Authority of Singapore, or MAS. It writes the rules, hands out the licenses, and checks that banks play fair. If you touch banking here, you answer to MAS. No way around it.
What Is a Digital Bank License in Singapore?
It is permission to run a bank that lives online, with no branches. MAS issued four of them back in 2020, and the bar was steep. Two for full banks that serve everyone. Two for wholesale banks that serve businesses. As of 2026, no new ones are being handed out.
Do You Need a License to Build a Banking App?
Short answer, no. The license is for the bank, not the builder. Your software partner does not need one to write the code. But here is the big catch. Whatever they build still has to meet MAS standards. So the partner has to know those standards cold.
What Are the MAS Technology Risk Management Guidelines?
People call them the TRM guidelines. They are the rulebook for banking tech. Uptime. Data handling. Fraud controls. How you recover when something breaks. A good build partner treats them as a checklist, not a surprise. Ask if they have read them. The right answer is yes, many times over.
What About Cloud and Outsourcing Rules?
Banks lean on the cloud now. MAS has rules for that too. Where your data lives. Who can touch it. What happens if a vendor fails. If your build runs on AWS or Azure, your partner needs to set it up the MAS way. Not the quick way.
What About KYC and Fraud Checks?
Every new customer has to be verified. That is KYC, short for know your customer. Add anti-money-laundering checks on top. These are not optional extras. They are baked into onboarding from day one, or the whole thing fails a review.
Are Customer Deposits Protected?
Yes, up to a point. Deposits at licensed digital banks are covered up to SGD 100,000 per person, per bank, under the deposit insurance scheme. Worth knowing if you are building for one. Trust is the real product here, and this is part of it.
How Do You Check if a Partner Is MAS-Ready?
Ask a plain question. Have you shipped something that held up under MAS scrutiny? A yes with proof is gold. A vague answer is a quiet red flag. Good partners know these rules by heart. They will not blink when you bring them up.
What Should You Actually Look For?
Everyone claims they can build a bank. The pitch decks all look the same. The logos, the buzzwords, the promises. But talk is cheap, and a banking build is not.
So how do you tell the real ones from the rest? You ask better questions. Here is a short gut-check before you sign anything.
- Have they built banking software before, or just generic apps? Banking has rules others do not.
- Do they hold the certificates that matter, like ISO 27001 and CMMI? Security is not a nice-to-have here.
- Will they stay after launch, or vanish once the invoice clears? A bank is never really finished.
- Does the price make sense for your market? Offshore and nearshore partners can cut cost hard without cutting quality.
Ask those four. Watch how they answer. The good ones lean in and give you specifics. The weak ones dodge, or bluff, or change the subject. That tells you almost everything. Trust the answers, not the pitch.
How Much Does All This Cost?
The honest answer? It depends. Nobody likes that answer, but it is true.
A ready platform has license fees, and they add up over time. A custom build has upfront cost but no rented ceiling. Where you build matters, too. A Singaporean firm and an offshore team can do similar work at very different rates. That gap is real, and it is why so many banks look toward partners with strong offshore delivery.
Rough rule of thumbs. Small app project, five figures. Full digital bank, six or seven figures and up. Get a few quotes. Compare like for like.
And watch the hidden costs. The building is only the start. Maintenance, updates, security patches, and support all follow, month after month. A partner who quotes cheap upfront but bills heavy later is not really cheap. Ask for the full picture before you sign. The running cost often matters more than the sticker price.
Final Thought
So, they are there. The top 20 digital banking solution companies in Singapore worth a look.
Here is the honest truth. There is no single best one. There is only the best one for you. So, pick by fit, not by fame.
Building from scratch? A custom partner like Brain Station 23 earns its keep. Buying a proven engine? Temenos or Backbase-led shops do the trick. Chasing app-store love? The design studios win.
Whatever you choose, ask the hard questions early. Check the certs. Read the answers, not the pitch. The right partner will not flinch, not once.
Frequently Asked Questions
How long does it take to build a digital bank?
Depends on what you are building. A ready-made bank-in-a-box can go live in a few weeks. A full custom bank takes many months, sometimes past a year. Scope drives it. So does how much has to pass a regulator. Small and standard is fast. Big and bespoke is slow.
Can a traditional bank go digital, or is this only for new banks?
Old banks can absolutely go digital. Most already are. It usually means modernising a creaky core, adding a fresh app, and moving services online bit by bit. You do not rip everything out on day one. You upgrade in stages, quietly, while the bank keeps running.
What is core banking modernization?
Core banking is the engine under the whole bank. The ledger, the accounts, the plumbing. Modernization means swapping an old, rigid core for something modern and flexible. Think of it as open-heart surgery for a bank. Risky if rushed, powerful when done right. Most big projects start right here.
Should you build an in-house team or hire a partner?
Both can work. An in-house team gives you full control, but hiring banking engineers is slow and pricey. A partner brings a ready team and real scars from projects like yours. Many banks mix the two. Core skills in-house, heavy lifting with a partner. Pick what your timeline can bear.
What is open banking?
It is banking that shares data through secure APIs, with your permission. Your bank can talk to other apps. A budgeting tool sees your spending. A lender checks your income. All with your yes. It makes switching and comparing easier. And it pushes banks to keep their apps sharp.
Does your build partner need to be based in Singapore?
No, and many are not. Plenty of strong teams serve Singapore from nearby hubs, working the same hours. What matters is not the postcode. It is whether they know the MAS rules and have shipped banking software before. Judge them on skill and track record, not their street address.
